
How do you upgrade or downgrade your APY pension slab, and what happens if monthly auto-debit fails?
1. What is Atal Pension Yojana (APY)?
Launched by the Government of India and regulated by the Pension Fund Regulatory and Development Authority (PFRDA), the Atal Pension Yojana (APY) is India's flagship statutory pension scheme targeted primarily at unorganized sector workers and self-employed individuals.
Administered through National Pension System (NPS) architecture, APY guarantees a fixed, lifelong monthly pension of ₹1,000, ₹2,000, ₹3,000, ₹4,000, or ₹5,000 starting at age 60, backed entirely by the Central Government. If accumulated returns on the pension corpus fall below the sovereign threshold, the deficit is funded directly by the Government of India.
Sovereign Guaranteed
100% government-backed lifelong pension with zero exposure to market downturns or NAV volatility.
Triple Benefit Structure
Pension to subscriber for life, then to spouse for life, and full return of corpus to nominee thereafter.
Flexible Contribution
Automated savings account debit on monthly, quarterly, or half-yearly basis from age 18 to 40.
2. Eligibility Criteria & The Income Taxpayer Exclusion Rule
To enroll in APY, applicants must fulfill strict statutory requirements under Ministry of Finance notifications:
3. The 5 Guaranteed Pension Slabs & Corpus Values
APY provides five distinct guaranteed pension slabs payable monthly from age 60 until death:
| Pension Slab | Monthly Lifelong Pension | Annual Pension Outflow | Guaranteed Return of Corpus to Nominee |
|---|---|---|---|
| Slab 1 | ₹1,000 / month | ₹12,000 / year | ₹1,70,000 |
| Slab 2 | ₹2,000 / month | ₹24,000 / year | ₹3,40,000 |
| Slab 3 | ₹3,000 / month | ₹36,000 / year | ₹5,10,000 |
| Slab 4 | ₹4,000 / month | ₹48,000 / year | ₹6,80,000 |
| Slab 5 (Recommended) | ₹5,000 / month | ₹60,000 / year | ₹8,50,000 |
4. How Auto-Debit Works: Frequencies & Timelines
APY operates exclusively through an automated standing instruction (auto-debit) from the subscriber's bank account:
Monthly Auto-Debit
Deducted on the designated date (typically between the 1st and 10th of every month). Most popular and convenient for salaried or wage earners.
Quarterly Auto-Debit
Debited once every 3 months (April, July, October, January). Suited for seasonal small vendors and MSME retail traders.
Half-Yearly Auto-Debit
Debited once every 6 months (April and October). Aligns well with agricultural harvesting cycles for farmers and rural workers.
5. Slab Upgrade & Downgrade Rules (PFRDA Guidelines)
Subscribers are not locked permanently into their initial pension choice. PFRDA permits upgrading or downgrading pension slabs under well-defined actuarial rules:
Upgrading to a Higher Pension Slab:
- Timing: Allowed once per financial year (preferably in the month of April).
- Differential Calculation: The subscriber must pay the difference in contributions from the original enrollment date up to the date of modification.
- Interest on Arrears: A compound interest of 8% per annum is charged on the differential arrears to maintain actuarial parity.
- Higher Future Debits: Future monthly auto-debits automatically adjust to the higher slab rate corresponding to your original entry age.
Downgrading to a Lower Pension Slab:
- Timing: Can be requested anytime during the financial year.
- Refund of Excess Corpus: The excess contribution accumulated in the PRAN is refunded back directly to the subscriber's linked savings bank account.
- Adjusted Deductions: Subsequent monthly debits immediately reduce to the lower slab contribution rate.
- No Penalty: Zero penalty is levied for reducing the pension slab.
6. Sovereign Guarantee & Nominee Corpus Return Rules
APY provides an unmatched three-tiered sovereign welfare cushion:
Phase 1 (Age 60 until Subscriber's Demise): The subscriber receives the guaranteed pension amount (e.g. ₹5,000/month) credited directly to their bank account every month.
Phase 2 (After Subscriber's Demise): The surviving spouse automatically receives the exact same monthly pension (₹5,000/month) for the rest of their natural life without deduction.
Phase 3 (After Demise of Both Subscriber & Spouse): The pension terminates, and the full predetermined corpus (₹8.5 Lakhs for the ₹5,000 slab) is handed over to the designated legal nominee.
7. Documents Required for APY Modification & Enrollment
- APY PRAN (Permanent Retirement Account Number): 12-digit PRAN allotted at original enrollment.
- Aadhaar Card: Mandatory for demographic validation and biometric KYC updates.
- Bank Passbook / Cancelled Cheque: Proving the active status of the auto-debit savings bank account.
- PFRDA APY Modification Form: Duly signed application indicating target revised pension slab.
- Nominee KYC Proof: Aadhaar/Voter ID of the registered nominee and spouse date of birth proof.
8. Step-by-Step Procedure to Change Pension Slab
Download APY Subscriber Modification Form
Download the official PFRDA Subscriber Modification Form for Atal Pension Yojana from the Protean CRA (npscra.nsdl.co.in) or collect it from your bank branch.
Select Target Pension Slab & Auto-Debit Mode
Fill in your 12-digit PRAN, name, and bank account number. Under Section B, tick the desired new monthly pension slab (e.g., upgrading from ₹1,000 to ₹5,000) and choose your contribution frequency.
Submit to Your Home Bank Branch
Submit the completed form to the home branch where your savings account is maintained. Maintain adequate balance in your account for the debit of differential arrears and the 8% interest charge.
Online Verification via APY e-PRAN Portal
Within 7 to 10 working days, visit the Protean CRA e-PRAN portal to download your updated APY Transaction Statement, verifying that the new monthly contribution rate and ₹5,000 pension entitlement are registered.
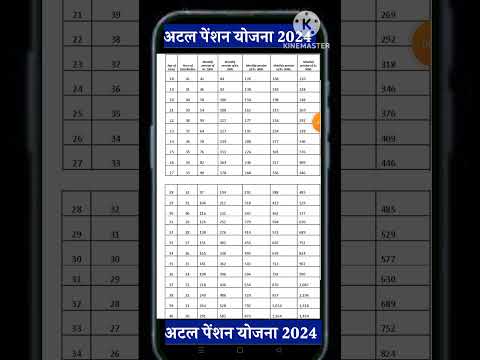
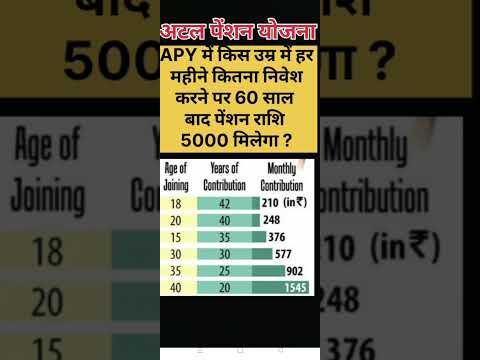
9. Age-wise Monthly Contribution Matrix for All 5 Slabs
The monthly contribution depends entirely on the subscriber's age at the time of joining:
| Entry Age | Tenure (Years) | ₹1,000 Pension | ₹2,000 Pension | ₹3,000 Pension | ₹4,000 Pension | ₹5,000 Pension |
|---|---|---|---|---|---|---|
| 18 Years | 42 | ₹42 / mo | ₹84 / mo | ₹126 / mo | ₹168 / mo | ₹210 / mo |
| 25 Years | 35 | ₹76 / mo | ₹151 / mo | ₹226 / mo | ₹301 / mo | ₹376 / mo |
| 30 Years | 30 | ₹116 / mo | ₹231 / mo | ₹347 / mo | ₹462 / mo | ₹577 / mo |
| 35 Years | 25 | ₹181 / mo | ₹362 / mo | ₹543 / mo | ₹722 / mo | ₹902 / mo |
| 40 Years (Cut-off) | 20 | ₹291 / mo | ₹582 / mo | ₹873 / mo | ₹1,164 / mo | ₹1,454 / mo |
10. Default Penalties & Inactivity Timelines
If auto-debit fails due to insufficient balance, banks levy statutory penal charges to ensure account restoration:
| Monthly Contribution Range | Overdue Fine Per Month |
|---|---|
| Up to ₹100 per month | ₹1 per month |
| ₹101 to ₹500 per month | ₹2 per month |
| ₹501 to ₹1,000 per month | ₹5 per month |
| Above ₹1,001 per month | ₹10 per month |
Chronological Inactivity Deadlines:
• 6 Months Continuous Default: The account is frozen; no deductions occur until arrears are cleared.
• 12 Months Continuous Default: The account is deactivated.
• 24 Months Continuous Default: The account is permanently closed, and remaining corpus is paid out.
11. Premature Exit & Voluntary Closure Rules
While APY is structured to continue until age 60, PFRDA permits voluntary premature closure under specific conditions:
- Demise of Subscriber Before Age 60: The spouse can choose to either continue the account until the subscriber would have reached 60 OR close the account and receive the accumulated corpus immediately.
- Terminal Illness: Immediate closure and full payout upon medical certification of specified life-threatening ailments.
- Voluntary Exit: If a subscriber voluntarily exits before age 60, only their own contributions along with net interest earned are refunded, after deducting account maintenance and fund management fees. Any government co-contribution and interest earned thereon is forfeited.
12. Income Tax Treatment (Section 80CCD)
Contributions to Atal Pension Yojana qualify for income tax deductions under the Old Tax Regime:
Section 80CCD(1)
Contributions qualify for tax deduction within the overall ₹1,50,000 cap of Section 80C.
Section 80CCD(1B) Additional ₹50,000
Subscribers can claim an exclusive additional deduction of up to ₹50,000 over and above the Section 80C limit for NPS/APY contributions.
13. Regulatory Oversight & PFRDA Statutory Framework
Pension Fund Regulatory and Development Authority (PFRDA): PFRDA (Atal Pension Yojana) Regulations, 2015 governing subscriber registration, fund allocation, and grievance redressal.
Central Recordkeeping Agency (CRA): Managed by Protean eGov Technologies (formerly NSDL CRA) for PRAN issuance and record maintenance.
Ministry of Finance Gazette Notification (F.No. 16/1/2015-PR): Establishing the sovereign deficit-funding guarantee for guaranteed pensions.
14. How to Choose: Why the ₹5,000 Slab is the Optimal Choice
Due to compounding inflation over a 20-to-40-year horizon, a ₹1,000 monthly pension will offer negligible purchasing power at age 60. Opting for the ₹5,000 monthly pension slab requires only ₹210/month at age 18 (or ₹577/month at age 30) and secures an ₹8,50,000 asset transfer to your nominee family, making it the mathematically superior choice.
15. Auto-Debit Maintenance Checklist for Subscribers
Recommended Video Tutorials & Practical Walkthroughs
Watch these handpicked, expert video guides covering practical compliance, step-by-step procedures, and real-world implementation:
Recommended Video Tutorials & Practical Guides
16. Frequently Asked Questions (FAQs)
Can an individual open two APY accounts in different banks?
No. An individual can open only one APY account. PRAN issuance is strictly linked to the subscriber's Aadhaar and PAN, and duplicate accounts are automatically flagged and rejected.
What happens if the subscriber changes their bank account?
Subscribers can transfer their APY auto-debit facility to a new bank account by submitting an APY Account Transfer Form along with a cancelled cheque of the new account to the new branch.
Can the pension amount increase beyond ₹5,000 if investment returns are high?
Yes! While ₹5,000 is the minimum government-guaranteed monthly pension, PFRDA regulations stipulate that if the accumulated return on investment exceeds the assumed actuarial returns, the actual pension paid to the subscriber will be proportionately enhanced.
17. Statutory References & Official Citations
PFRDA Official Portal: pfrda.org.in (Pension Fund Regulatory and Development Authority).
Protean CRA APY Services: npscra.nsdl.co.in (Central Recordkeeping Agency).
Ministry of Finance (DFS): Financial Inclusion Division - Atal Pension Yojana Master Guidelines.