Quick Summary & Key Takeaways (Featured Snippet)
2. Consortium Banking: Lead Bank Mandate, Joint Appraisal & Common Covenants
Consortium banking is a formalized, unified debt syndicate governed by collective legal agreements:
- Designated Lead Bank: The bank holding the largest credit share (typically 30% to 50% of the aggregate facility) acts as the Lead Bank (e.g., State Bank of India or Bank of Baroda).
- Single Techno-Economic Viability (TEV) Study: The Lead Bank conducts the detailed credit appraisal, financial modeling, and engineering due diligence. Member banks adopt the Lead Bank's appraisal without duplicating costly studies.
- Common Loan Agreement (CLA): The borrower executes a standardized, unified credit agreement binding all member banks to identical interest rate spreads, margin requirements, and financial covenants.
- Joint Lenders Meetings (JLM): Consortium members meet quarterly to review company quarterly information system (QIS) performance, drawing power allocations, and stock audit reports.
3. Multiple Banking Arrangements (MBA): Independent Limits & Parallel Exposure
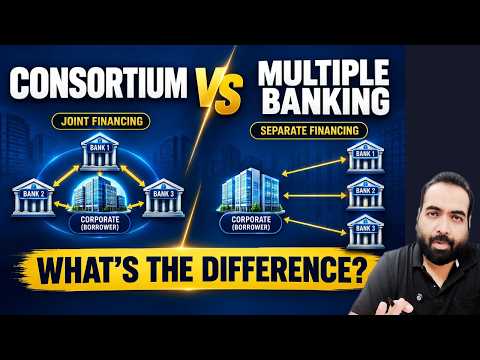
In contrast to a consortium, a Multiple Banking Arrangement (MBA) is an uncoordinated, fragmented credit structure:
Separate Credit Lines
The borrower approaches Bank A for a ₹20 Crore cash credit line, Bank B for a ₹30 Crore term loan, and Bank C for a ₹15 Crore Letter of Credit limit. Each bank executes separate loan agreements with different covenants and margins.
Revenue Routing Disparity
Because there is no centralized escrow or Lead Bank oversight, borrowers frequently route customer sales collections through their favorite bank while neglecting accounts at other lenders, creating serious non-performing asset (NPA) risks.
4. The Legal Backbone: Inter-Creditor Agreement (ICA) & Voting Thresholds
The legal operational manual that binds member banks together is the Inter-Creditor Agreement (ICA):
Collective Decision-Making Rules
Under standard Indian consortium ICAs, major corporate borrowing decisions—such as restructuring debt, granting additional working capital, or waiving covenants—are decided by a collective vote:
- Value Voting Threshold: Typically requires lenders representing at least 66% to 75% of total outstanding debt value.
- Headcount Voting Threshold: Requires at least 60% of lenders by number to prevent a single mega-bank from bulldozing smaller consortium participants.
- Binding Effect: Decisions approved by the requisite majority are legally binding upon all dissenting minority consortium members.
5. Security Creation: First Pari-Passu Charge & Trust & Retention Accounts (TRA)
First Pari-Passu Security Charge
Rather than each bank attempting to carve out specific factory buildings or machinery, a unified Security Trustee (e.g., SBICAP Trustee or Catalyst Trusteeship) holds a joint First Pari-Passu charge on all fixed and current assets for the shared benefit of all lenders.
Trust and Retention Account (TRA)
A non-negotiable cash control escrow mechanism. All operational revenue must be deposited into the TRA with the Lead Bank. Funds are automatically distributed according to a predetermined statutory cash waterfall.
6. Consortium Banking vs Multiple Banking Arrangements (MBA) Matrix
| Governance Feature | Consortium Banking | Multiple Banking Arrangements (MBA) |
|---|---|---|
| Leadership & Appraisal | Single Lead Bank conducts appraisal | Independent appraisals by each bank |
| Loan Documentation | Common Loan Agreement & single ICA | Separate bilateral agreements per bank |
| Collateral Security | Shared First Pari-Passu charge via Trustee | Competing, uncoordinated security charges |
| Cash Flow Management | Single TRA Escrow account mandated | Fragmented accounts across multiple banks |
| Borrower Flexibility | Rigid; requires joint consortium approval | High; borrower negotiates terms individually |
7. Regulatory Vigilance: RBI Information-Sharing Directives & CRILC Reporting
Following high-profile banking frauds where rogue promoters exploited uncoordinated Multiple Banking Arrangements to divert borrowed funds, the RBI issued stringent compliance mandates:
Mandatory Information Exchange & CRILC Integration
- RBI Master Circular on Lending Under MBA: Mandates that all banks in an MBA must exchange written quarterly credit information detailing sanctioned limits, drawing power utilized, and audit red flags before renewing limits.
- CRILC (Central Repository of Information on Large Credits): Scheduled commercial banks must report aggregate credit exposures of ₹5 Crores and above to the RBI's central database on a real-time weekly basis. Any default exceeding 30 days (SMA-1) is instantly broadcast to all lenders nationwide.
8. Step-by-Step Corporate SOP: Migrating from MBA to a Structured Consortium
Mandate Lead Bank & Determine Debt Slices
Select a dominant public or private sector bank as Lead Arranger. Allocate underwriting tickets (e.g., Lead Bank ₹100 Cr, Bank B ₹75 Cr, Bank C ₹50 Cr).
Appoint Security Trustee & Draft Inter-Creditor Agreement
Appoint a licensed SEBI Debenture/Security Trustee. Execute the ICA formalizing voting thresholds, drawing power formulas, and default remedies.
Establish TRA Escrow & File CERSAI Charges
Open the Trust and Retention Account with the Lead Bank. Register joint first pari-passu security charges on Form CHG-1 with the RoC and on the CERSAI portal.
9. Stressed Asset Workouts: RBI June 7 Prudential Framework & Resolution Plans
When a multi-bank borrower faces financial distress, resolution is governed by the RBI Prudential Framework for Resolution of Stressed Assets (June 7, 2019 Circular):
Upon a default occurring across any single member bank, all lenders enter a mandatory 30-day Review Period. During this window, all lenders must sign an ICA to formulate a comprehensive Resolution Plan (RP) within 180 days.
Consortium lending dramatically accelerates this process because an ICA and voting structure already exist. In an uncoordinated MBA, inter-bank disputes over collateral ranking frequently delay debt restructuring, dragging viable enterprises into corporate liquidation under the IBC.
10. Top Corporate Governance Pitfalls & Restrictive Covenant Checklist
Key Operational Hazards to Avoid
- Opening Unapproved Current Accounts Outside Consortium: Under RBI guidelines, borrowers cannot open current accounts with non-lending banks. Siphoning collections outside the consortium violates covenants and leads to immediate facility recall.
- Delayed Submission of Monthly Stock Statements: Failing to submit joint stock and debtor statements by the 10th of every month freezes drawing power across all member banks.
- Uncoordinated Capex Without Syndicate Approval: Incurring major capital expenditure without Lead Bank techno-economic approval constitutes a material event of default.
Recommended Video Tutorials & Practical Walkthroughs
Watch these handpicked, expert video guides covering practical compliance, step-by-step procedures, and real-world implementation:
Recommended Video Tutorials & Practical Guides