
What is Sukanya Samriddhi Yojana (SSY) and how does the maturity math build a ₹70 Lakh tax-free corpus?
1. The Girl Child Savings Flagship: What is the SSY Scheme?
Launched under the Government of India’s visionary Beti Bachao Beti Padhao campaign, the Sukanya Samriddhi Yojana (SSY) was notified on December 2, 2014, and subsequently codified under the Sukanya Samriddhi Account Rules, 2019 (Ministry of Finance Notification G.S.R. 914(E)).
Unlike ordinary recurring bank deposits or Public Provident Fund (PPF) accounts, SSY carries a targeted social mandate: to systematically dismantle gender bias and eliminate financial hurdles associated with female education and marriage by offering the highest interest spread among all administered small savings schemes.
100% Sovereign Guarantee
Deposits and accrued returns are backed by the Consolidated Fund of India, carrying zero credit default risk.
8.2% Highest Debt Yield
Commands an attractive premium over 10-year G-Sec yields, offering 110 bps higher interest than standard PPF (7.1%).
Complete EEE Tax Immunity
Contribution, accumulation, and withdrawal phases are all completely immune to Indian income tax and capital gains.
2. Statutory Eligibility Criteria & Beneficiary Age Limits
Rule 3 and Rule 4 of the Sukanya Samriddhi Account Rules, 2019 establish unambiguous statutory boundaries regarding who can open and operate an account:
Beneficiary Profile & Age Threshold
The account can be opened exclusively in the name of a girl child who is a resident Indian citizen from the exact moment of birth until she reaches 10 years of age. If a girl was born on August 15, 2016, her account must be opened on or before August 14, 2026.
Guardian Status & Number of Accounts per Family
The account must be opened and operated by a natural parent (mother or father) or a court-appointed legal guardian. A maximum of two accounts per family (one per girl child) is permitted.
The Twin / Triplet Statutory Exception
Under Rule 3(3), more than two accounts can be opened in a single family if twin or triplet girls are born in the first delivery, or if a single girl is born in the first delivery followed by twin or triplet girls in the second delivery, verified by a medical birth certificate signed by an authorized municipal medical officer.
3. Deposit Slabs, 15-Year Contribution Period & 21-Year Maturity
The SSY lifecycle follows a distinct bifurcated timeline structured over 21 years from the date of account opening:
| Phase Period | Duration | Deposit Obligation | Interest Accumulation Status |
|---|---|---|---|
| Active Deposit Phase | Years 1 to 15 | Mandatory minimum ₹250 / year; maximum ₹1,50,000 / year. | Compounds quarterly at notified rate (currently 8.2%). |
| Passive Compounding Phase | Years 16 to 21 | Zero deposits accepted. Parent makes no further payments. | Entire corpus continues to compound annually at government rates. |
| Maturity Event | End of Year 21 | Account closes. Balance credited to girl child’s personal bank account. | No interest accrues beyond 21 years; immediate closure mandatory. |
4. The 8.2% Compounding Math: How ₹22.5 Lakh Becomes ₹70 Lakh
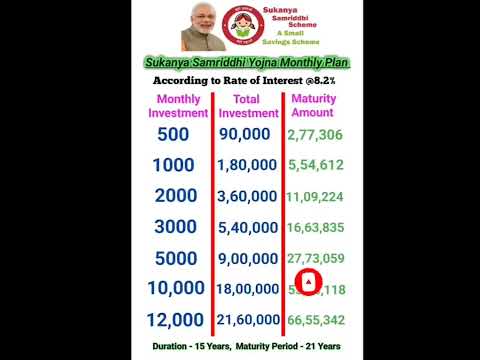
The interest under SSY is determined on a quarterly basis by the Ministry of Finance and credited to the account at the end of each financial year. The mathematical beauty lies in the 6 years of passive compounding where ₹0 fresh capital is introduced, yet the accumulated principal mushrooms aggressively:
The Compound Interest Formulation (Annuity with Deferred Maturity)
Phase 1 (15 Years Annuity): A₁₅ = P × [((1 + r)¹⁵ - 1) / r] × (1 + r)
Phase 2 (6 Years Deferred Compounding): Maturity Value = A₁₅ × (1 + r)⁶
• P: ₹1,50,000 deposited on April 5th every year
• r: 8.2% annual interest (effective compounding rate)
• Total Principal Deposited over 15 Years: ₹22,50,000
• Total Interest Earned: ₹47,60,000 to ₹48,50,000
• Total Tax-Free Maturity Value: ₹70,10,000 to ₹71,00,000
5. Triple Tax Exemption: Section 80C & Section 10(11A) EEE Status
SSY represents the gold standard of statutory tax shielding in India, categorised under the Exempt-Exempt-Exempt (EEE) framework:
Section 80C Deduction
Deposits up to ₹1,50,000 per financial year qualify for income tax deduction under Section 80C of the Income Tax Act, 1961 (Old Tax Regime).
Section 10(11A) Exemption
Annual interest accrued and credited to the account is 100% tax-free under Section 10(11A). No TDS is deducted, and no tax clubbing applies under Section 64.
100% Tax-Free Corpus
The entire terminal payout at 21 years (whether ₹20 Lakhs or ₹70 Lakhs) is completely exempt from income tax and long-term capital gains tax.
6. 50% Partial Withdrawal Rules for Higher Education at Age 18
Rule 8 of the Sukanya Samriddhi Account Rules allows a one-time partial liquidity window to ensure the girl child’s higher academic ambitions are never compromised:
- Age & Educational Trigger: Withdrawal is permitted only after the girl child attains the age of 18 years or has passed the 10th standard.
- Maximum Quantum: Up to 50% of the account balance standing to her credit at the end of the preceding financial year.
- Disbursement Modes: Can be availed as a single lump-sum payout or in five equal annual installments corresponding to academic university degree semesters.
- Mandatory Evidentiary Proof: A confirmed letter of admission from a recognized educational institution along with the official fee structure detailing tuition and hostel charges must accompany the Form 3 application.
7. Mandatory Documents for Opening Accounts
To open an SSY account at any India Post Office branch or authorized public/private commercial bank, the applicant must present:
Girl Child Documentation
- • Official Birth Certificate issued by Registrar of Births & Deaths / Municipal Corporation
- • Aadhaar Card of the girl child (or Aadhaar Enrolment Slip)
- • Recent passport-size photographs (2 copies)
- • Medical Certificate from Chief Medical Officer (in case of twins/triplets)
Parent / Guardian Documentation
- • Aadhaar Card & PAN Card of Father/Mother/Legal Guardian
- • Proof of Address (Electricity bill, Passport, Voter ID if different from Aadhaar)
- • Initial opening deposit cheque/cash (minimum ₹250)
- • Legal Guardianship Order issued by a competent court (if applicable)
8. Step-by-Step Account Opening SOP via IPPB & Commercial Banks
Step 1: Obtain & Fill Form-1 (SSY Account Opening Form)
Collect the standard statutory Form-1 from any authorized post office or bank branch (SBI, PNB, Canara, HDFC, ICICI, Axis). Enter child's birth details and parent KYC data.
Step 2: Attach Certified Proofs & Submit Initial Deposit
Attach self-attested copies of the girl child's birth certificate, guardian's PAN, and Aadhaar card. Deposit initial opening amount (minimum ₹250, maximum ₹1,50,000) in cash or bearer cheque.
Step 3: Account Activation & Physical Passbook Issuance
Upon verification, the branch issues a physical SSY Passbook stamped with the unique SSY Account Number, CIF ID, child's name, date of birth, and date of maturity.
Step 4: Enable Digital Standing Instructions (IPPB / Net Banking)
Link the SSY account number to India Post Payments Bank (IPPB) mobile app or your commercial bank's internet banking portal to automate monthly or annual UPI/NEFT standing deposits.
9. SSY vs PPF vs Equity Mutual Funds vs SGB Comparison Matrix
| Investment Parameter | Sukanya Samriddhi (SSY) | Public Provident Fund (PPF) | Equity Mutual Funds (SIP) | Sovereign Gold Bonds (SGB) |
|---|---|---|---|---|
| Current Yield / Return | 8.2% Sovereign Fixed | 7.1% Sovereign Fixed | 12% – 14% Market-Linked | 2.5% + Gold Capital Apprec. |
| Tax Exemption Status | EEE (100% Tax-Free) | EEE (100% Tax-Free) | LTCG Taxable at 12.5% (> ₹1.25 Lakh) | LTCG Tax-Free on Maturity |
| Lock-in Period | 21 Years (or marriage >18) | 15 Years | Zero (3 Yrs for ELSS) | 8 Years |
| Max Annual Investment | ₹1,50,000 | ₹1,50,000 | Unlimited | 4 kg per Individual |
| Capital Guarantee | 100% Sovereign Backed | 100% Sovereign Backed | Market Risk Borne by Investor | Sovereign Debt Backed |
10. Real-World Maturity Projections: ₹50,000 vs ₹1,50,000 Annual Deposit
Scenario A: The ₹1.5 Lakh Maximum Annual Deposit Plan
Deposits: ₹1,50,000 deposited on April 1 each year for 15 consecutive years (Total invested: ₹22,50,000).
Accumulation: At year 15, the corpus reaches ~₹43,80,000. It compounds silently with zero deposits for the next 6 years.
Terminal Payout at 21 Years: ₹70,45,000 Tax-Free. The child receives over ₹47.9 Lakhs purely in compounding interest, providing complete funding for medical, engineering, or international master's degree tuition.
Scenario B: The Moderate ₹50,000 Annual Deposit Plan
Deposits: ₹50,000 deposited annually for 15 years (Total invested: ₹7,50,000).
Accumulation & Maturity: At year 15, the balance stands at ~₹14,60,000. By year 21, the accumulated terminal payout reaches ₹23,48,000 Tax-Free.
11. Audit Pitfalls, Account Default Fines & Re-activation Rules
Critical Default Pitfalls
- • Failure to Deposit Minimum ₹250: If ₹250 is not deposited in any financial year, the account is categorized as 'Account in Default'. Defaulted accounts only earn Post Office Savings Account rate (4.0%) unless regularized.
- • Exceeding the ₹1.5 Lakh Annual Cap: Any deposit exceeding ₹1,50,000 in a financial year earns zero interest and is refunded immediately without tax benefit.
- • Timing Deposits After the 5th of the Month: Interest is calculated on the minimum balance between the 5th and the last day of each month. Depositing on the 6th causes you to forfeit an entire month’s interest.
Re-activation SOP
- • Statutory Penalty: Pay a default fee of ₹50 per defaulted year.
- • Arrear Deposits: Deposit the minimum ₹250 for each lapsed year along with the current financial year’s deposit.
- • Submission: Submit Form-2 at the home branch to restore full 8.2% compounding status.
12. Statutory Premature Closure & Medical Emergency Grounds
Under Rule 7 of the Sukanya Samriddhi Account Rules, 2019, premature closure before the completion of 21 years is strictly restricted to three exceptional statutory grounds:
1. Tragic Demise of the Girl Child: Upon production of a valid Death Certificate issued by the competent authority, the account is closed immediately. The principal and accrued interest calculated up to the date of demise are handed over to the legal guardian.
2. Life-Threatening Medical Diseases: Premature closure is permitted after 5 years from account opening if the guardian demonstrates severe financial distress due to medical treatment of life-threatening diseases of the girl child or demise of the guardian who was maintaining the account, certified by an authorized medical specialist.
3. Marriage of the Girl Child after Age 18: If the girl child marries after attaining the age of 18, the account can be closed prematurely by submitting an affidavit affirming her marriage age accompanied by the wedding invitation and proof of age. The application must be submitted between 1 month prior to marriage and up to 3 months post-marriage.
13. Legal Aspects: Guardianship, NRI Status & Adoption
Change in Residential Status (NRI Trigger): If the girl child or the guardian acquires non-resident Indian (NRI) status or surrenders Indian citizenship, the account is deemed closed from the date of change of citizenship. No interest accrues beyond that date, and the accumulated balance must be repatriated or credited to an NRO account.
Legally Adopted Daughters: A legally adopted girl child enjoys 100% equal statutory status under SSY. A certified copy of the Court Adoption Order under the Hindu Adoptions and Maintenance Act or the Juvenile Justice (JJ) Act serves as valid legal authority to open and maintain the account.
Operational Handover at Age 18: When the girl child attains the age of 18 years, the guardian ceases to have operational control. The girl child must submit fresh KYC documents, her PAN, and an updated signature specimen at the bank/post office to assume sole direct ownership of the account.
14. Decision Matrix: When to Pick SSY vs Equity Mutual Funds
| Parent's Financial Profile | Recommended Investment Allocation | Strategic Rationale |
|---|---|---|
| Conservative / Risk-Averse Parent | 100% SSY (₹1.5 Lakh / Year) | Guarantees zero capital drawdown with an unbeatable 8.2% sovereign debt yield and zero tax friction. |
| Balanced / Long-Term Wealth Creator | 50% SSY (Debt) + 50% Equity Index SIP | SSY serves as the sovereign capital-guaranteed bedrock while index equities beat long-term higher-education inflation. |
| High Net-Worth Individual (HNI) | Max ₹1.5L SSY + Flexi-cap Equity Funds | Maximizes the annual Section 80C tax shield and captures the entire tax-free ₹70 Lakh sovereign corpus. |
15. Parent’s Annual Compliance & Deposit Checklist
- Deposit your annual contribution between April 1 and April 5 to earn interest for all 12 full months.
- Ensure the aggregate deposit in a single financial year does not exceed the statutory ceiling of ₹1,50,000.
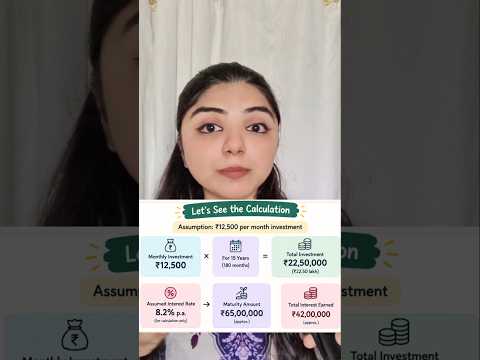
- Set up an automated monthly ECS / NACH standing instruction if investing in monthly tranches (e.g., ₹12,500/month).
- Get the physical passbook updated at your bank or post office branch at least once every financial year after March 31.
- Claim the annual deposit amount under Section 80C while filing your Income Tax Return (ITR-1 or ITR-2) under the Old Regime.
- Initiate the operational transfer of the account to your daughter on her 18th birthday by updating her personal PAN and signature.
Recommended Video Tutorials & Practical Walkthroughs
Watch these handpicked, expert video guides covering practical compliance, step-by-step procedures, and real-world implementation:
Recommended Video Tutorials & Practical Guides
16. Frequently Asked Questions (FAQs)
17. Statutory Sources & Official Portal Directory
- • Ministry of Finance (DEA) Small Savings Notifications: https://dea.gov.in
- • India Post Sukanya Samriddhi Portal: https://www.indiapost.gov.in
- • Reserve Bank of India Small Savings Master Circular: https://rbi.org.in
- • Income Tax Department Section 80C & Section 10(11A) Provisions: https://incometax.gov.in