Which are the best zero balance current accounts in India for small businesses, sole proprietors, and freelancers?
For a true unconditional ₹0 Monthly Average Balance (MAB) with physical branch access, Bank of Baroda (bob LITE Current Account) and Axis Bank (Delite Current Account) are India's top choices, offering ₹0 monthly maintenance fees, free QR/Soundbox benefits, and 50 free cheque leaves. For registered startups (Pvt Ltd, LLP, OPC), IDFC FIRST Bank Startup Current Account and AU Bank Zero2One provide a 3-year ₹0 MAB waiver with up to ₹30 Lakh/month free cash deposits. For shopkeepers and professionals seeking instant Video KYC opening without GST, AU Power Current Account (waived on 1 monthly ₹100 transaction), Airtel Payments Bank Current Account, IndusInd Freedom, and neo-banking platforms Tide Business and RazorpayX deliver seamless zero-balance digital banking.
Unconditional zero balance on BoB LITE, Axis Delite, Airtel PB & Tide
Free monthly cash deposit + 3-Year ₹0 MAB on IDFC FIRST Startup CA
Open legally without GST using Udyam + Shop Act/IEC (or 1 doc with Bank CPV)
Annual capital bleed saved by avoiding ₹1,500/mo + 18% GST MAB shortfall fines
1. Understanding the 4 Types of “Zero Balance” Current Accounts in India
When Indian entrepreneurs search for a zero balance current account, bank marketing brochures often blur the line between unconditional lifetime waivers and conditional promotional offers. Unlike savings accounts—where the Reserve Bank of India (RBI) mandates Basic Savings Bank Deposit Accounts (BSBDA) and prohibits banks from turning balances negative due to non-maintenance fees—commercial current accounts are governed by bilateral tariff contracts.
Before submitting your PAN and business KYC, you must identify which of the four commercial structures an account actually belongs to. Choosing the wrong bucket can trigger unexpected quarterly service charges once an introductory period expires or when seasonal sales dip.
These scheduled commercial bank accounts carry a permanent ₹0 Monthly Average Balance (MAB) and ₹0 Quarterly Average Balance (QAB) requirement in their official Schedule of Service Charges. Even if your balance remains ₹0 for six consecutive months during an off-season, no non-maintenance penalty is levied. Top examples include Bank of Baroda bob LITE Current Account, Axis Bank Delite Current Account, Airtel Payments Bank Current Account, AU Royale Business (for CAs & CS), and Federal Bank Fed Arogya (for Healthcare).
Designed for retail shopkeepers, supermarkets, pharmacies, and restaurants, these accounts waive their standard ₹10,000–₹25,000 MAB requirement whenever you route merchant collections through the bank's UPI Soundbox or POS swipe terminal. For instance, the AU Small Finance Bank Power Current Account becomes 100% zero-balance by completing just one transaction of ₹100 per month, while IndusInd Freedom and IDFC FIRST Merchant Zero Balance waive MAB based on monthly digital/QR settlement volume.
Tailored for newly incorporated Private Limited Companies, LLPs, One Person Companies (OPCs), and DPIIT-recognized startups, these premium accounts grant a complete holiday on minimum balance maintenance for the first 12 to 36 months. IDFC FIRST Startup Current Account and AU Zero2One offer 3 years of ₹0 MAB; Bank of Baroda bob Start-up offers 2 years of ₹0 MAB; and SBI Shubharambh, ICICI iStartup 2.0, and Kotak Startup CA offer 1 year of ₹0 MAB.
Digital-first platforms like Tide Business, RazorpayX, and Open Financial partner with RBI-regulated banks (RBL, YES Bank, ICICI, Axis) to provide lifetime zero-balance digital accounts with automated accounting and API payouts. Meanwhile, PSU and private variants like Indian Overseas Bank (IOB) Freedom Current Account and Axis Local Current Account replace monthly balance tracking with a predictable flat annual subscription fee.
2. Interactive Zero-Balance Account Finder & MAB Savings Calculator
Use the interactive selector below to match your business entity, GST availability, and monthly physical cash deposit volume against India's top 15 commercial current accounts, and compute your exact annual savings:
Interactive Zero-Balance Current Account Finder & MAB Savings Calculator
Filter 15 commercial banks by your business structure, GST status, and monthly cash deposit volume
Top 3 Recommended Accounts for Your Profile
Filtered for Non-GST KYC (Udyam + Alternative Proof)Bank of Baroda bob LITE Current Account
Best all-round PSU account: True ₹0 MAB, 1 Free Soundbox QR device, 100% waiver on POS/MPOS monthly rental, 50 free cheque leaves, and eligible for up to ₹25L collateral-free Overdraft.
Axis Bank Delite Current Account
Google's #1 ranked private-bank zero balance current account specifically built for retail shopkeepers, sole proprietors, and local traders.
AU Small Finance Bank Power Current Account
Zero MAB activated by a single ₹100 monthly transaction, free UPI QR Soundbox option, and Video KYC opening even without GST.
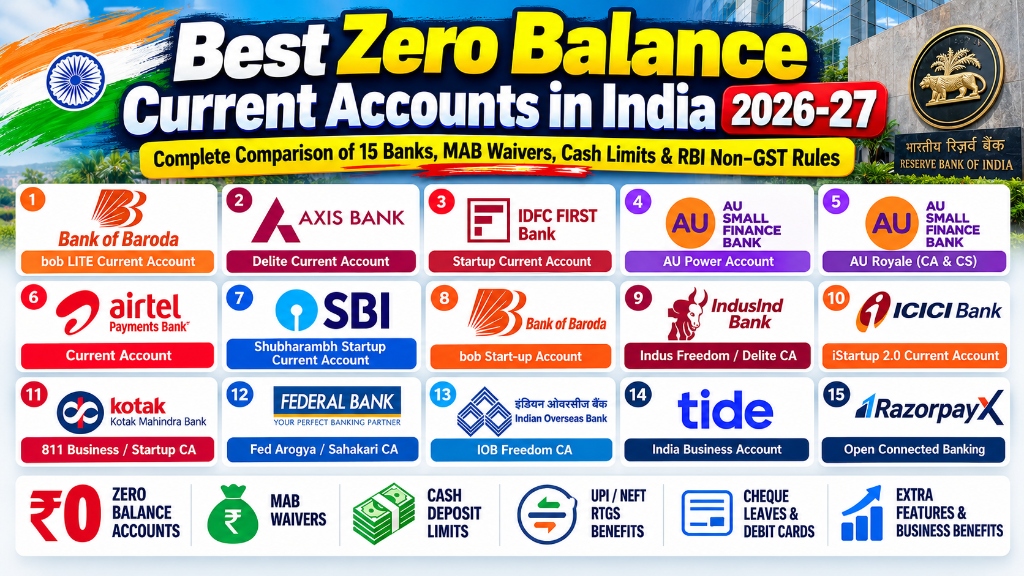
3. Master Comparison: Top 15 Zero Balance & Startup Current Accounts in India (2026-27)
The comprehensive comparison matrix below benchmarks all 15 leading commercial accounts across Public Sector Banks (PSUs), Private Sector Banks, Scheduled Small Finance Banks, Payments Banks, and Neo-Banking platforms. Every row reflects verified 2026–2027 tariff rules:
| Bank & Account Variant | Category | MAB / Waiver Condition | Free Monthly Cash Deposit | Online NEFT / RTGS / IMPS | Standout Perks & Overdraft | Best Suited For |
|---|---|---|---|---|---|---|
| 1. Bank of Baroda — bob LITE Current Account | PSU Bank | ₹0 Unconditional Forever | Up to 1,000 notes/day (CDMs & Branches) | Free Digital UPI/NEFT | 1 Free Soundbox QR, 50 free cheque leaves, Collateral-Free OD up to ₹25 Lakh, VISA Vyapaar Card | Sole proprietors, traders & professionals |
| 2. Axis Bank — Delite Current Account | Private Bank | ₹0 MAB & ₹0 Monthly Fee | ₹1,00,000 / month (Base) | Free Online NEFT/RTGS | Choice of Business Classic, Supreme, or Platinum Debit Card; zero monthly service charges | Retailers, shopkeepers & MSMEs |
| 3. IDFC FIRST Bank — Startup Current Account | Private Bank | ₹0 MAB for First 3 Years | ₹30,00,000 / month Free | 100% Free IMPS/NEFT/RTGS | BRAVO Auto-Sweep FD (up to 7.10%), Free GPS Doorstep Banking, VISA Signature Card (Lounge + ₹1Cr Cover) | Pvt Ltd, LLP & OPC startups (<3 yrs) |
| 4. AU Small Finance Bank — AU Power Account | Small Finance Bank | ₹0 MAB (1 Txn of ₹100/mo) | Dynamic (Up to 25x AMB / Merchant Tier) | Free via AU 0101 App | Video KYC opening without GST; instant UPI QR & Soundbox; Zero2One gives 3-Yr Startup MAB waiver | Micro-merchants & non-GST proprietors |
| 5. AU Small Finance Bank — AU Royale (CA & CS) | Small Finance Bank | ₹0 Lifetime Unconditional | ₹5,00,000+ / month | 100% Free Digital Transfers | Custom account number matching CA/CS membership ID; tax & ERP software discounts | Practicing CAs & Company Secretaries |
| 6. Airtel Payments Bank — Current Account | Payments Bank | ₹0 Unconditional Forever | Via Airtel Banking Points | 100% Free UPI & IMPS | Paperless Aadhaar + PAN KYC in minutes; instant voice alerts (₹2 Lakh EOD balance limit) | Small kirana stores & solo traders |
| 7. SBI — Shubharambh Startup Current Account | PSU Bank | ₹0 MAB for 1st Year | ₹15,00,000 / month Free | Free Online + 10 Free DDs/mo | 100 free cheque leaves/mo, Free PRIDE Business Debit Card, Free POS installation + 20% rental discount | DPIIT Startups (Regular SBI CA is ₹5k MAB) |
| 8. Bank of Baroda — bob Start-up Account | PSU Bank | ₹0 MAB for First 2 Years | ₹50,000 / day (~₹15L/mo) | Free NEFT/RTGS/IMPS for 2 Yrs | 200 free cheque leaves/month for 2 years, Auto-Sweep facility, complimentary corporate credit card | Early-stage scalable startups |
| 9. IndusInd Bank — Indus Freedom / Delite CA | Private Bank | ₹0 MAB (POS/Digital Active) | ₹1,00,000 to ₹4,00,000 / mo | Free Online NEFT/RTGS/IMPS | 100% Video KYC account opening with zero branch visit; custom account number; Auto-Sweep FD | Retailers, distributors & exporters |
| 10. ICICI Bank — iStartup 2.0 Current Account | Private Bank | ₹0 MAB for First 1 Year | ₹2,00,000 / month Free | Free via InstaBIZ / CIB | Best-in-class InstaBIZ mobile app, integrated Zoho/Tally reconciliation, inward/outward forex desk | Tech startups & SaaS founders |
| 11. Kotak Mahindra — 811 Business / Startup CA | Private Bank | ₹0 Digital / 1-Yr Startup Waiver | ₹1,00,000 to ₹2,50,000 / mo | Free Online NEFT/RTGS | ActivMoney 2-way Auto-Sweep FD (up to 7% p.a.), doorstep cash/cheque pickup on Startup Premium | Digital businesses & funded startups |
| 12. Federal Bank — Fed Arogya / Sahakari CA | Private Bank | ₹0 MAB (Sector Specific) | ₹2,00,000+ / month | Free Online Transfers | Zero balance for hospitals, clinics, diagnostic labs & co-op societies (Trade Silver gives 1-Yr free Soundbox) | Doctors, clinics, pharmacies & labs |
| 13. Indian Overseas Bank — IOB Freedom CA | PSU Bank | ₹0 MAB (Annual Fee Model) | Bundled in Annual Plan | No Folio Charges + 30+ Services | Pay a single predictable annual fee to maintain ₹0 balance all year with 30+ free banking services | Seasonal traders & contractors |
| 14. Tide India Business Account | Neo-Bank (RBL Partner) | ₹0 Lifetime Free | Digital Only (Partner CDM extra) | Unlimited Free UPI & IMPS | Free Expense Card, built-in GST invoice generator, receipt scanning, 10-minute mobile KYC | Freelancers, solo consultants & creators |
| 15. RazorpayX / Open Connected Banking | Neo-Bank (RBL/YES/Axis) | ₹0 Lifetime Free (Base Tier) | Via Partner Bank Branch/CDM | Automated API Bulk Payouts | Direct TDS/GST portal payment, payroll automation, maker-checker approvals, webhook APIs | E-commerce brands, D2C & agencies |
4. In-Depth Analysis: India's Top 12 Zero Balance & Startup Current Accounts
A surface-level table never tells the full story of how branch managers, cash recyclers, and automated billing systems treat your account after opening. Below is a granular, practitioner-grade breakdown of the top 12 accounts—covering their exact eligibility rules, free quotas, and hidden fine print.
1. Bank of Baroda: bob LITE Current Account & bob Start-up Account
For sole proprietors, shopkeepers, and independent professionals who want the safety and nationwide branch footprint of a premier Public Sector Bank without locking up working capital, the bob LITE Current Account is unmatched. Unlike private bank accounts that hide transaction-volume conditions in footnotes, Bank of Baroda mandates a flat ₹0 Monthly Average Balance across rural, semi-urban, urban, and metro branches alike. Account holders receive one complimentary Soundbox QR device, a 100% waiver on monthly rental charges for POS/MPOS machines, 50 free cheque leaves upon opening, and a VISA Vyapaar DI Debit Card. Even more impressively, businesses can apply for a collateral-free Overdraft (OD) limit of up to ₹25 Lakh under MSME/CGTMSE norms once transaction history is established, and deposit up to 1,000 currency notes per day free of cost across branches, CDMs, and Cash Recyclers.
If you are launching a scalable Private Limited Company, LLP, or registered Partnership startup, Bank of Baroda also offers the bob Start-up Current Account, which waives MAB requirements for a full 2 years (24 months), provides 200 free cheque leaves every month, waives NEFT/RTGS/IMPS charges for 2 years (with a 50% concession thereafter), and allows free cash deposits up to ₹50,000 per day alongside an integrated Auto-Sweep facility.
2. Axis Bank: Delite Current Account & Local Current Account
Axis Bank dominates commercial search rankings in India with its dedicated Delite Current Account, engineered specifically for retail merchants, sole proprietors, and local businesses. The Delite variant eliminates both the Monthly Average Balance requirement and recurring monthly service charges, giving small business owners access to Axis Bank's corporate internet banking, mobile app, and customizable Business Classic, Supreme, or Platinum debit cards. On the Business Supreme and Platinum cards, your first 5 ATM transactions per month remain free after a single POS swipe, and personal accident insurance stays active when the card is swiped once every 90 days.
For higher-volume local traders who deposit up to ₹3 Lakh per month in physical cash and execute up to 75 cash withdrawals, Axis Bank also offers the Axis Local Current Account, which replaces monthly balance anxieties with a flat annual subscription fee of ₹1,999 + GST. When cash deposits exceed the free monthly ceiling on Axis variants, the bank charges ₹4 per ₹1,000 (up to ₹20 Lakh) and ₹5 per ₹1,000 beyond ₹20 Lakh.
3. IDFC FIRST Bank: Startup Current Account & Merchant Zero Balance CA
Among Indian startup founders on Reddit (`r/indianstartups`) and venture debt circles, IDFC FIRST Bank is widely regarded as the gold standard for modern business banking. Its Startup Current Account (available to Private Limited Companies, LLPs, and OPCs incorporated within the last 3 years) offers an unmatched 3-year (36-month) unconditional ₹0 AMB waiver—triple the duration of ICICI or SBI. Even more remarkably, it grants a massive ₹30 Lakh per month free cash deposit limit, 100% free and unlimited IMPS, NEFT, and RTGS transfers, free GPS-enabled doorstep banking at one business location, and zero setup or Annual Maintenance Charges (AMC) on payment gateways, UPI/QR codes, and virtual accounts.
Furthermore, IDFC FIRST's signature BRAVO Auto-Sweep facility automatically sweeps idle current account balances into Fixed Deposits earning up to 7.10% p.a. with zero premature withdrawal penalty whenever funds are needed for business payments. Founders also get a complimentary VISA Signature Business Debit Card (featuring ₹1 Crore personal accident cover and complimentary domestic airport lounge access) and an FD-backed Step-Up Corporate Credit Card. For non-startup sole proprietors and professionals, IDFC FIRST offers dedicated ZERO Balance Accounts for Merchants and Professionals tied to QR/POS settlements or professional practice credentials.
4. AU Small Finance Bank: AU Power Account, Royale (CA/CS) & Zero2One Startup
As an RBI-scheduled Small Finance Bank (upgrading to Universal Bank status), AU Small Finance Bank has built three distinct zero-balance pathways. First, for everyday shopkeepers, freelancers, and sole proprietors, the AU Power Current Account waives its entire minimum balance requirement to ₹0 as long as you complete at least one transaction of ₹100 or more per month. Crucially, AU Bank allows individuals and sole proprietors to open a Digital Current Account online via Video KYC from home without a mandatory GST certificate (using PAN, Aadhaar, and alternative business proof).
Second, for practicing Chartered Accountants (CAs) and Company Secretaries (CS), the AU Royale Business Account provides a lifetime unconditional ₹0 minimum balance, a customized bank account number Incorporating your ICAI/ICSI membership digits, and preferential discounts on ERP and tax compliance software. Third, for incorporated startups, the AU Zero2One Program matches IDFC FIRST by offering a 3-year AMB waiver, FD-backed corporate credit cards, and API banking.
5. Airtel Payments Bank & India Post Payments Bank (IPPB) Current Accounts
Micro-retailers, vegetable/fruit vendors, small repair shops, and gig-economy entrepreneurs often struggle to produce two formal municipal or tax certificates. Airtel Payments Bank solves this with a 100% digital Zero Balance Current Account that can be opened using digital KYC with Aadhaar and PAN, offering zero minimum balance and 100% free UPI and IMPS transactions. Similarly, India Post Payments Bank (IPPB) offers a zero-MAB merchant current account with doorstep postman onboarding.
Statutory Caveat to Remember: Under RBI Guidelines for Licensing of Payments Banks, neither Airtel Payments Bank nor IPPB can hold more than ₹2,00,000 per customer at the end of the day (EOD) (unless excess funds are automatically swept into a partner scheduled commercial bank account), and Payments Banks cannot directly issue in-house credit cards or working capital loans.
6. State Bank of India (SBI): Shubharambh Startup CA & Regular Current Account
One of the highest-volume search queries on Google is “SBI zero balance current account.” Here is the verified statutory truth from SBI's official SME Schedule of Service Charges: SBI offers the Shubharambh Startup Current Account (for DPIIT-recognized Private Limited Companies, LLPs, Registered Partnerships, and OPCs up to 10 years from incorporation with turnover under ₹100 Crore). Shubharambh provides ₹0 MAB for the first 12 months (after which a ₹20,000 MAB applies), a massive ₹15,00,000 per month free cash deposit limit (valid across Home/Non-Home branches, CDMs, and Cash Recyclers), 100 free multicity cheque leaves per month, 10 free Demand Drafts per month, a free PRIDE Business Debit Card, and free POS terminal installation with a 20% discount on monthly POS rentals.
What if you are a regular sole proprietor or trader without a DPIIT startup certificate? SBI does not offer a permanent ₹0 MAB general current account (unless linked to a high-volume SBI Power POS machine), but SBI's Regular Current Account requires a Monthly Average Balance of just ₹5,000—the lowest standard MAB among major Indian banks—and includes free monthly cash deposits of 100 times your previous month's MAB (up to ₹5,00,000/month) plus 50 free cheque leaves per month, with Video KYC onboarding now live on the SBI portal.
7. IndusInd Bank (Indus Freedom & Delite CA)
Video KYC LiveIndusInd Bank allows sole proprietors and individuals to open a current account online via 100% Video KYC without visiting a branch and pick a custom account number (e.g., matching your mobile number). While Indus Delite caps free cash deposits/withdrawals at ₹1 Lakh (or 4 transactions) per month, Indus Freedom offers up to ₹4 Lakh/month free cash deposit and waives MAB completely when linked to active POS/QR merchant throughput. Excess cash attracts ₹5 per ₹1,000 (min ₹150).
8. ICICI Bank (iStartup 2.0 Current Account)
1-Year ₹0 MABTargeted at new startups (up to 10 years old), ICICI iStartup 2.0 Silver and Gold variants waive MAB for the first 12 months and provide ₹2,00,000 per month in free cash deposits. Its killer advantage is the ICICI InstaBIZ & Corporate Internet Banking (CIB) ecosystem, which natively integrates with Zoho Books and Tally Prime and handles inward/outward foreign exchange (SWIFT/FIRC) faster than almost any legacy bank.
9. Kotak Mahindra (811 Business & Startup CA)
ActivMoney 7% SweepKotak offers two strong entry points: the digital-first Kotak811 Business Current Account for micro-entrepreneurs looking for zero balance maintenance, and the Kotak Startup Regular / Premium Current Account, which waives Average Quarterly Balance (AQB) non-maintenance charges for the first 12 months (standard ₹50,000 AQB applies from Year 2) and pairs with ActivMoney two-way auto-sweep FDs.
10. YES Bank (Blitz / Head Start-Up / Smart Edge)
API & UPI LeaderFor new-to-bank businesses and startups, YES Bank Blitz and YES Head Start-Up offer zero or waived AMB tiers with free online NEFT/RTGS and ₹2 Lakh to ₹10 Lakh monthly cash deposit limits. YES Bank also powers the backend banking rails for major fintech neo-banks, offering a 3-tier auto-upgrade current account architecture where fees drop as your business balance scales.
11. Federal Bank (Fed Arogya) & IOB Freedom CA
2026 Tariff UpdateImportant 2026 Alert: Federal Bank officially discontinued its general ₹5,000 MAB Freedom Current Account effective April 1, 2026, replacing its zero-balance focus with Fed Arogya (₹0 MAB for doctors, clinics, hospitals, and labs) and Fed Sahakari (₹0 MAB for co-operative institutions). Meanwhile, PSU lender Indian Overseas Bank (IOB Freedom CA) lets any business maintain ₹0 balance all year by paying a single upfront annual fee that bundles 30+ free services and zero ledger folio charges.
12. Tide Business, RazorpayX & Open (Neo-Banks)
₹0 Lifetime DigitalIf 100% of your revenue arrives via UPI, payment gateways, IMPS, or NEFT and you never deposit physical cash bundles, neo-banking platforms Tide India, RazorpayX, and Open Financial (partnered with RBL, YES, ICICI, and Axis) require ₹0 minimum balance for life. You get instant virtual corporate cards, automated vendor payout APIs, and 1-click GST/TDS challan settlements.
5. Schedule of Charges Audit: Excess Cash Fees, Cheque Books, Debit Cards & Auto-Sweep
Even when a bank waives the Monthly Average Balance, commercial tariff sheets generate revenue from five secondary fee heads: excess physical cash handling, non-home branch deposits, physical debit card Annual Maintenance Charges (AMC), bulk outward IMPS fees, and early account closure penalties within 12 months. Review this secondary fee schedule before signing your account opening form:
| Bank / Platform | Excess Cash Deposit Charge (Above Free Limit) | Free Cheque Leaves | Business Debit Card AMC | Auto-Sweep (FFD) Interest | Account Closure Fee (<12 Months) |
|---|---|---|---|---|---|
| Bank of Baroda (bob LITE) | Standard BoB Cash Handling above 1,000 notes/day | 50 Free Leaves (200/mo on Startup) | VISA Vyapaar DI (Standard tariff) | Yes (on bob Start-up / Premium) | ₹500 – ₹1,000 + GST |
| Axis Bank (Delite / Local) | ₹4/₹1,000 (up to ₹20L); ₹5/₹1,000 (>₹20L) | 25 to 50 Leaves / month | ₹250 – ₹750 + GST (Classic/Supreme/Plat) | Available via Auto-FD Sweep | ₹500 – ₹1,000 + GST |
| IDFC FIRST (Startup CA) | Free up to ₹30L/mo; ₹4/₹1,000 beyond | Unlimited / High Free Quota | ₹0 Free VISA Signature Card | BRAVO Sweep (Up to 7.10% p.a., 0 Penalty) | Nil / Standard Slab |
| AU Small Finance Bank | ₹4/₹1,000 above free tier | 25 to 100 Leaves / month | ₹199 – ₹500 + GST (Free on Royale) | Yes (Flexi Sweep FD) | ₹500 + GST (15 days–1 yr) |
| SBI (Shubharambh / Regular) | Free up to ₹15L (Startup) / ₹5L (Reg); ₹0.75–₹2/₹1k after | 100/mo (Startup) | 50/mo (Regular) | Free PRIDE Business Debit Card | Yes (Surabhi / Multi-Option Deposit) | ₹500 + GST (15 days–1 yr) |
| IndusInd Bank (Freedom / Delite) | ₹5/₹1,000 (Min ₹150 per transaction) | Free Monthly Quota | ₹299 – ₹699 + GST (Virtual Free) | Yes (Auto-Sweep Deposit) | ₹500 – ₹1,000 + GST |
| Tide / RazorpayX / Open | Digital Only (Partner CDM fees apply) | Partner Bank Dependent | ₹0 Free Virtual / Expense Card | Via Partner Bank RBL/YES/ICICI | ₹0 Account Closure Fee |
6. How to Open a Zero Balance Current Account Without a GST Number (RBI Section 32 Blueprint)
Under Section 22 of the Central Goods and Services Tax (CGST) Act, 2017, businesses supplying services with an aggregate annual turnover up to ₹20 Lakh (or ₹40 Lakh for exclusive intra-state supply of goods) are legally exempt from mandatory GST registration. Yet thousands of Indian freelancers, home bakers, tuition teachers, kirana owners, and new sole proprietors are wrongly turned away at bank branches by staff demanding a GST certificate.
Under Section 32 of the RBI Master Direction – Know Your Customer (KYC) Direction, 2016, GST registration is never a mandatory precondition for opening a sole proprietorship current account. The RBI requires any two government-issued documents proving business activity—and even includes a special Single-Document Discretion Proviso allowing banks to open the account with just ONE document (such as your free Udyam Certificate) after conducting a physical Contact Point Verification (CPV). Follow this 6-step blueprint to open your account in 24 to 48 hours without GST:
Generate Free Udyam Registration (Proof #1)
Visit the official Ministry of MSME portal (udyamregistration.gov.in) and generate your Udyam Registration Certificate using your Aadhaar and PAN in 10 minutes at ₹0 cost. Ensure you enter your exact trade name (e.g., M/s Apex Digital Studio) and select “No / Exempt” under the GSTIN field.
Obtain Your Second Entity Document (Proof #2)
Pair your Udyam Certificate with any ONE of these fast, low-cost statutory proofs in the same trade name: (a) State Shop & Establishment (Gumasta) License, (b) Import Export Code (IEC) from the DGFT portal (costs ₹500 online in 1 hour—ideal for freelancers), (c) FSSAI Basic Registration (₹100/yr for food sellers), or (d) Professional Tax / Municipal Trade License.
Or Invoke the RBI Single-Document CPV Proviso
If you operate from home and only have a Udyam Certificate, cite the Proviso to Section 32 of the RBI KYC Master Direction. When a bank is satisfied that procuring two documents is not feasible, it can legally accept only one document plus a physical Contact Point Verification (CPV) visit by a field officer to verify your workspace.
Prepare Your Rubber Stamp & Address Proof
For offline or doorstep verification, get a ₹150 proprietorship rubber stamp reading “For [Your Trade Name] — Proprietor”. If your business operates from a rented shop or residence, keep the registered Rent Agreement + latest Electricity/Water bill (and a simple No-Objection Certificate if the utility bill is in a parent's or spouse's name).
Choose a Non-GST Friendly Zero-Balance Bank
Apply directly via Video KYC or branch at banks known for smooth non-GST onboarding: AU Small Finance Bank (Digital/Power CA via Video KYC), Bank of Baroda (bob LITE), Airtel Payments Bank (Aadhaar+PAN), IndusInd Bank (Video KYC), or Tide Business (accepts Udyam on mobile app).
Complete Video KYC & Activate Soundbox/Sweep
Keep your original physical PAN card, blank white paper, and black/blue pen ready during the 5-minute Video KYC call. Once your account number and IFSC are active, immediately link your business UPI QR and enable Auto-Sweep (if supported) so surplus funds earn FD interest.
7. RBI Mandatory KYC Document Matrix by Legal Constitution
Documentation requirements differ sharply depending on whether your business is an unincorporated proprietorship or a separate legal entity registered with the Ministry of Corporate Affairs (MCA) or Registrar of Firms. Use this official RBI checklist to prepare your digital PDF docket:
| Business Constitution | Entity PAN Requirement | Mandatory Entity Existence & Activity Proofs | Signatory & Beneficial Owner KYC |
|---|---|---|---|
| 1. Individual / Freelancer (In Own Name) | Personal PAN Card | Udyam Certificate / Professional Qualification Certificate (ICAI, ICSI, Medical Council, Bar Council) / ITR | Aadhaar e-KYC + Live Video KYC / CPV |
| 2. Sole Proprietorship (In Trade Name) | Proprietor's Personal PAN | Any TWO in Firm Name: Udyam Certificate, GSTIN, Shop & Establishment License, IEC, FSSAI, Professional Tax, or CA Certificate + Utility Bill (or 1 doc + Bank CPV) | Proprietor PAN + Aadhaar + Firm Rubber Stamp |
| 3. Partnership Firm | Separate Firm PAN Card | Partnership Deed, Registration Certificate (if registered), GST/Udyam/Shop Act, Partnership Authority Letter signed by all partners | PAN & Officially Valid Document (OVD) of all partners holding >10%–15% share & authorized signatories |
| 4. Limited Liability Partnership (LLP) | LLP Entity PAN Card | Certificate of Incorporation (MCA), Executed LLP Agreement (Form 3), Resolution of Designated Partners authorizing bank operations | PAN, Aadhaar/OVD & DPIN of Designated Partners + Ultimate Beneficial Owner (UBO) declaration |
| 5. Private Limited / OPC Company | Company PAN Card | Certificate of Incorporation (COI), Memorandum & Articles of Association (MOA & AOA), Board Resolution on company letterhead, MCA Master Data | PAN, DIN & OVD of Directors / Authorized Signatories + UBO declaration (>10% ownership) |
8. RBI Circular on Current Account Discipline: Rules for Businesses with CC / OD Loans
Before opening a secondary zero-balance current account, every business owner with an active bank loan must check compliance with the landmark RBI Circular DOR.No.BP.BC/7/21.04.048/2020-21 (dated August 6, 2020) and its consolidated relaxation circular DOR.CRE.REC.63/21.04.048/2021-22 (dated October 29, 2021) on “Opening of Current Accounts by Banks – Need for Discipline.” The Reserve Bank enacted these binding norms to stop corporate borrowers from availing Cash Credit (CC) or Overdraft (OD) limits at one bank while diverting sales receipts through unmonitored current accounts at another bank.
Under the revised RBI framework, your freedom to open a current account depends on your aggregate credit exposure across the entire Indian banking system (including fund-based and non-fund-based limits):
Zero Restriction: Even if you have a Mudra Loan, MSME Cash Credit, or Overdraft facility, if your total credit exposure across all banks is less than ₹5 Crore, you can freely open a current account with any bank—provided you sign a standard undertaking promising to notify the bank if your aggregate credit facilities ever reach ₹5 Crore.
Lending Bank Rule: If you avail CC/OD facilities and your aggregate exposure is between ₹5 Crore and ₹50 Crore, only lending banks that hold at least 10% of your total banking exposure can open a full current account for you. Non-lending banks are strictly barred from opening regular current accounts and may only open restricted Collection Accounts.
Mandatory Escrow Mechanism: Borrowers with banking system exposure of ₹50 Crore or more must establish an Escrow Account with one lending bank. Other lending banks can open Collection Accounts, provided all funds credited are swept into the central Escrow/CC/OD account within 2 working days, with zero debit card or cheque-issuing rights on collection accounts.
9. Special Guide for Freelancers, SaaS Founders & Exporters: SWIFT, e-FIRA & Tax Rules
If you are an Indian software developer, UI/UX designer, digital marketer, agency founder, or Upwork/Fiverr freelancer billing clients in USD, EUR, GBP, or AED, using a personal savings account for recurring commercial inward remittances violates bank terms of service and frequently triggers account freezes during FEMA compliance audits. Furthermore, under GST law, export of services is treated as a Zero-Rated Supply under Section 16 of the IGST Act, 2017—meaning you pay 0% GST under a Letter of Undertaking (LUT), provided your bank issues a valid Electronic Foreign Inward Remittance Advice (e-FIRA / FIRC) carrying RBI Purpose Code P0802 (Software Consultancy) or P1007 (Business & Management Consulting).
Traditional banks routinely charge a steep ₹1.50 to ₹2.50 per USD forex conversion spread plus ₹500–₹1,000 per physical FIRC certificate. To maximize take-home income, pair a zero-balance current account—such as Bank of Baroda bob LITE, IDFC FIRST Bank, IndusInd Freedom, or AU Digital CA—with an RBI-compliant cross-border payment aggregator (such as Skydo, Wise Business, or Payoneer). You receive local US ACH / UK Sort Code receiving accounts, settle INR directly into your zero-balance current account at the live mid-market Google rate, and download automated digital e-FIRA PDFs at zero extra bank balance cost. Simultaneously, independent professionals with gross receipts up to ₹75 Lakh (where cash receipts do not exceed 5%) can declare just 50% of gross receipts as taxable income under Section 44ADA of the Income Tax Act without maintaining complex audit books.
10. Verified Expert Insights & Commercial Banking Practitioner Disclosures
Read field-tested compliance observations from practicing Chartered Accountants, MSME treasury advisors, and startup banking specialists across India:
“Whenever a branch relationship manager tells a new sole proprietor that GST registration is mandatory for a current account, hand them a printed copy of Section 32 of the RBI Master Direction on KYC. Combining a free Udyam Certificate with an IEC or Shop Act license—or invoking the RBI Single-Document CPV proviso—is 100% legally binding across all scheduled banks.”
“Early-stage Pvt Ltd and LLP founders often open a 1-year waiver account and get hit with ₹2,500/month non-maintenance charges in Month 13 when pre-revenue runway tightens. Opting for a 3-year ₹0 AMB startup program like IDFC FIRST Startup CA or AU Zero2One with automated Flexi-FD sweep protects 36 months of runway while earning up to 7.10% on idle seed capital.”
“A zero-balance current account can still cost a wholesale kirana trader ₹4,000/month if they ignore the free cash deposit cap! Depositing ₹10 Lakh/month in a ₹1 Lakh limit account triggers ₹4–₹5 per ₹1,000 + 18% GST on the ₹9 Lakh excess. High-cash businesses should use BoB LITE (1,000 notes/day) or SBI Shubharambh (₹15L/mo free).”
“Receiving $3,000/month from US SaaS clients into a personal savings account is the #1 reason Indian freelancers face sudden lien locks. Open a ₹0 MAB current account (BoB LITE, AU Digital, or IndusInd Video KYC) so your trade name matches your GST LUT and e-FIRA certificates seamlessly.”
11. Verified Video Walkthroughs: Live Account Opening, BoB LITE & Video KYC Demos
Watch these 4 verified practical tutorials demonstrating the exact eligibility rules, tariff breakdowns, and live Video KYC onboarding workflows for Bank of Baroda bob LITE, AU Small Finance Bank, and India's top zero-balance current accounts:
12. Frequently Asked Questions (FAQs) on Zero Balance Current Accounts
Here are verified answers to the 12 most searched questions by Indian sole proprietors, freelancers, and startup founders:
Which bank offers a true unconditional zero balance current account in India?▼
Bank of Baroda (bob LITE Current Account), Axis Bank (Delite Current Account), and Airtel Payments Bank offer true unconditional ₹0 Monthly Average Balance (MAB) current accounts with zero monthly non-maintenance penalties. Additionally, AU Small Finance Bank offers the AU Royale Business Account at ₹0 lifetime MAB for Chartered Accountants and Company Secretaries, while Federal Bank offers the Fed Arogya ₹0 MAB account exclusively for doctors, clinics, diagnostic centers, and hospitals.
Can a sole proprietorship or freelancer open a zero balance current account without a GST number?▼
Yes. Under Section 32 of the RBI Master Direction on Know Your Customer (KYC), a GST certificate is not mandatory to open a current account. A sole proprietor or freelancer can open an account using personal KYC (PAN and Aadhaar) plus any two business entity proofs in the firm's name—such as a free Udyam Registration Certificate combined with a Shop & Establishment License, Import Export Code (IEC), Professional Tax Certificate, FSSAI License, or ITR. Furthermore, under the RBI Single-Document Proviso, banks have the statutory discretion to accept just one document (such as Udyam alone) after conducting a physical Contact Point Verification (CPV).
How does the AU Small Finance Bank Power Current Account zero balance waiver work?▼
The AU Power Current Account operates on a simple activity-based waiver. While the base account is structured for retail merchants and traders, the Monthly Average Balance requirement is completely waived to ₹0 whenever the account holder completes at least one QR code or POS transaction of ₹100 or more during the calendar month.
Does State Bank of India (SBI) offer a zero balance current account?▼
SBI offers the Shubharambh Startup Current Account, which provides a 100% waiver on Monthly Average Balance (MAB) for the first 12 months (and ₹20,000 MAB thereafter) for DPIIT-recognized startups registered as Private Limited Companies, LLPs, Registered Partnerships, or OPCs. It includes ₹15 Lakh per month in free cash deposits and 100 free cheque leaves per month. For regular sole proprietors who do not qualify as DPIIT startups, SBI's Regular Current Account carries the lowest PSU maintenance threshold at ₹5,000 MAB with free cash deposits up to ₹5 Lakh per month.
Which zero balance startup current account gives the longest MAB waiver for Private Limited companies and LLPs?▼
IDFC FIRST Bank (Startup Current Account) and AU Small Finance Bank (Zero2One Startup Program) provide the longest initial maintenance holiday in India, offering a 3-year (36-month) unconditional ₹0 AMB waiver for startups incorporated within the last 3 years. Bank of Baroda's bob Start-up Current Account ranks second with a 2-year (24-month) ₹0 MAB waiver and 200 free cheque leaves per month, while ICICI Bank iStartup 2.0 and SBI Shubharambh provide a 1-year (12-month) MAB waiver.
Does HDFC Bank or Kotak Mahindra Bank have a zero balance current account?▼
Kotak Mahindra Bank offers the Kotak811 Business digital current account with zero balance requirements for eligible micro-entrepreneurs, as well as a 1-year AQB non-maintenance waiver on its Startup Regular and Premium current accounts. HDFC Bank does not offer an unconditional lifetime zero balance current account for general private businesses (its ₹0 MAB institutional account is restricted to government bodies), though HDFC SmartUp and merchant POS-linked current accounts waive monthly balance requirements when specified card swipe or QR settlement milestones are met.
What is the penalty for not maintaining Minimum Average Balance (MAB) in a regular current account?▼
Unlike savings accounts where RBI mandated that non-maintenance penalties cannot turn an account balance negative, commercial current accounts have no statutory fee cap. Traditional banks require ₹10,000 to ₹1,00,000 in Monthly or Quarterly Average Balance and deduct ₹500 to ₹3,000 plus 18% GST every month (₹7,080 to ₹42,480 annually) if your balance drops below the threshold.
What are the RBI rules on opening a current account if my business has a Cash Credit (CC) or Overdraft (OD) loan?▼
Under RBI Circular DOR.No.BP.BC/7/21.04.048/2020-21 and the October 2021 revised framework on Current Account Discipline, borrowers with aggregate banking system exposure below ₹5 Crore can open a current account upon submitting an undertaking to notify the bank once exposure touches ₹5 Crore. Borrowers with CC/OD facilities and aggregate exposure of ₹5 Crore or more must maintain their current account with a lending bank that holds at least 10% of the exposure; other banks can only open collection accounts that auto-sweep funds to the primary CC/OD account within 2 working days.
Can I earn interest on idle funds lying in a zero balance current account?▼
By RBI regulation, banks cannot pay direct savings interest on standard current account balances. However, banks like IDFC FIRST Bank (BRAVO Auto-Sweep), Bank of Baroda (bob Start-up Auto-Sweep), Kotak Mahindra Bank (ActivMoney), and IndusInd Bank allow you to enable an automated Flexi Fixed Deposit (FFD) sweep. Surplus funds above a chosen threshold automatically convert into short-term fixed deposits earning 5.5% to 7.10% p.a. and seamlessly break on a Last-In-First-Out (LIFO) basis whenever you issue a cheque or payment.
What is the difference between a Neo-Bank account (Tide, RazorpayX, Open) and a traditional bank current account?▼
Neo-banks (fintech platforms like Tide, RazorpayX, and Open) are not independent RBI-licensed banks; they operate as technology layers partnered with scheduled commercial banks such as RBL Bank, YES Bank, ICICI Bank, or Axis Bank. Neo-banks offer ₹0 balance accounts, instant virtual cards, automated GST invoicing, and bulk API vendor payouts, but they lack physical bank branches for cash deposits, demand drafts, Letters of Credit (LC), or Bank Guarantees (BG).
Which zero balance current account is best for Indian freelancers receiving Upwork, Fiverr, or US/UK client payments?▼
Freelancers exporting IT, design, consulting, or marketing services require low forex conversion markups and automated Electronic Foreign Inward Remittance Advice (e-FIRA / FIRC) to claim zero-rated GST export benefits under LUT. IDFC FIRST Bank, IndusInd Freedom/Delite, and ICICI Bank (paired with Skydo, Wise Business, or Payoneer) provide smooth SWIFT inward remittance processing and digital e-FIRA generation without forcing freelancers to lock ₹50,000 in dead MAB capital.
Are deposits in zero balance current accounts and Small Finance Banks insured by RBI?▼
Yes. All scheduled commercial banks—including Public Sector Banks (SBI, Bank of Baroda, IOB), Private Sector Banks (Axis, IDFC FIRST, ICICI, IndusInd, Kotak, Federal), Small Finance Banks (AU Small Finance Bank, Equitas, Jana), and Payments Banks (Airtel Payments Bank, IPPB)—are compulsorily insured by the Deposit Insurance and Credit Guarantee Corporation (DICGC), a wholly owned subsidiary of the RBI, up to ₹5,00,000 (principal plus interest) per depositor per bank.
Complete Your Business Banking & GST Compliance Stack
Explore our related statutory manuals on How to Write a Cancelled Cheque Safely for KYC, UPI Transaction Limits & Merchant MDR GST Rules, and UPI 24-Hour ₹5,000 Cooling Period Rules.