
Which is the best Nifty 50 Index Fund for long-term SIP wealth creation in India?
The UTI Nifty 50 Index Fund and HDFC Index Nifty 50 Fund consistently rank as the top choices for Indian retail investors due to massive AUM (providing immense liquidity during market crashes), ultra-low tracking error under 0.03%, and competitive Direct Plan expense ratios (around 0.18% to 0.20%). Over rolling 15-year horizons, a ₹10,000 monthly SIP in the Nifty 50 TRI has compounded at a historical average of 13.2% XIRR, growing an invested principal of ₹18 Lakh into over ₹68 Lakh.
1. What is a Nifty 50 Index Fund?
A Nifty 50 Index Fund is an open-ended mutual fund scheme that passively mirrors the composition of the Nifty 50 Index managed by NSE Indices Ltd. It holds the shares of the top 50 largest, most liquid companies listed on the National Stock Exchange (NSE) weighted by free-float market capitalization.
Unlike actively managed funds where a portfolio manager attempts to beat the market by stock picking (and charges up to 2% in fees), an index fund manager does not attempt to time the market. The fund simply replicates the index, delivering market returns with rock-bottom expense ratios.
2. Who Should Build Their Core Portfolio on Index Funds?
- Salaried Employees: Looking for a "set-it-and-forget-it" automated monthly SIP for 10–25 year retirement or child education goals.
- Disillusioned Active Investors: Over 85% of active large-cap mutual funds in India fail to beat the Nifty 50 benchmark after deducting management fees (SPIVA India Scorecard).
- Conservative Equity Beginners: Wanting bluechip safety (Reliance, TCS, HDFC Bank, Infosys) without single-stock downfall risk.
3. Index Mutual Funds vs Exchange Traded Funds (ETFs)
| Parameter | Nifty 50 Index Mutual Fund | Nifty 50 ETF (e.g. NIFTYBEES) |
|---|---|---|
| Demat Account Required? | No (Direct via AMC / MF Central) | Yes (Mandatory Broker Demat) |
| SIP Automation | Seamless auto-debit on fixed date | Requires broker stock-SIP feature |
| Pricing & NAV | End-of-day NAV (Zero spread slippage) | Real-time market price (bid-ask spread risk) |
| Transaction Costs | ₹0 brokerage, ₹0 DP charges | Brokerage + STT + DP selling charges |
4. How Replication & Sector Weights Work
The fund manager invests incoming SIP capital in exact proportion to the free-float market weight of the 50 constituents. Top sectors driving the Nifty 50 include:
Financial Services
~31.5%
Information Tech
~13.8%
Oil, Gas & Fuels
~11.2%
Fast Moving Consumer
~8.9%
5. SEBI Regulations & Index Rebalancing Rules
NSE Indices reconstitutes the Nifty 50 semi-annually in March and September. Under SEBI portfolio replication rules:
- The fund must invest at least 95% of total assets in securities of the benchmark index.
- When a stock is evicted from the index and replaced, the fund manager must execute the portfolio transition within 7 business days.
6. Total Expense Ratio (TER) & Tracking Error Benchmark
Why 0.10% Matters Over 25 Years:
A regular large-cap fund charging 1.75% vs an index fund charging 0.15% represents a 1.60% annual drag. On a ₹10,000 monthly SIP compounding at 12% gross return over 25 years, that 1.6% fee difference burns away over ₹32 Lakh of your final wealth!
7. Account Setup & KYC Documentation
1. PAN Card: Mandatory for all Indian mutual fund investments.
2. Aadhaar Card: Linked with PAN for digital OTP e-KYC.
3. Cancelled Cheque / Bank Statement: Verifying IFSC and account number for SIP NACH auto-debits.
8. Step-by-Step SIP Setup SOP
Step 1: Choose Direct Plan - Growth Option
Always select "Direct Plan - Growth". Never select "Regular Plan" (which pays hidden distributor commissions) or "IDCW / Dividend Option" (which triggers annual tax on dividends).
Step 2: Set Up Monthly SIP on Salary Credit Date
Schedule your monthly auto-debit 1 to 2 days after your monthly salary hits your bank account (e.g. 3rd or 5th of every month).
Step 3: Enable 10% Annual Step-Up SIP
Activate the annual step-up feature to increase your SIP amount by 10% each year matching your salary increments, doubling your 20-year corpus.
9. Benchmark: Top 5 Nifty 50 Index Funds in India (2026)
| Scheme Name | AUM (₹ Cr) | Direct TER | 3-Yr Tracking Error | Verdict |
|---|---|---|---|---|
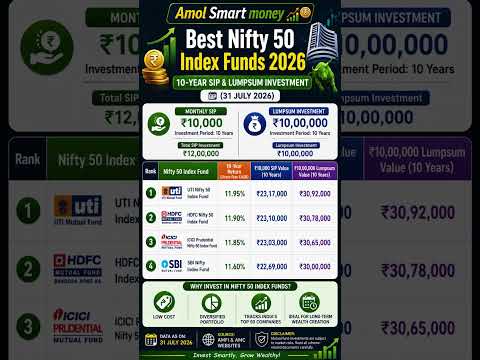
| UTI Nifty 50 Index Fund | ₹18,500+ Cr | 0.18% | 0.02% | Top Overall Pick |
| HDFC Index Fund - Nifty 50 | ₹15,200+ Cr | 0.20% | 0.03% | Excellent Liquidity |
| ICICI Prudential Nifty 50 Index | ₹10,100+ Cr | 0.17% | 0.04% | Solid Bluechip Track |
| Nippon India Index Fund - Nifty 50 | ₹2,800+ Cr | 0.15% | 0.04% | Good Mid-AUM Choice |
| Navi Nifty 50 Index Fund | ₹1,900+ Cr | 0.06% | 0.05% | Lowest Expense |
10. Real-World Wealth Simulation: 15-Year ₹10,000 Monthly SIP
Compounding Simulation (15 Years @ 13.2% XIRR):
11. Common Investor Mistakes in Index Investing
1. Stopping SIPs During Market Corrections
Halting SIPs when the Nifty drops 10% to 20% destroys compounding. Market crashes are when your SIP buys the maximum number of index units at discounted valuations.
2. Chasing Regular Plans Through Bank Relationship Managers
Bank RMs will push "Regular Plans" because the AMC secretly pays them trail commissions out of your fund value every year for life!
12. Risks & Sector Concentration
The primary risk of the Nifty 50 is sector concentration: over 31% is concentrated in Financial Services. If a banking crisis hits India, the Nifty 50 experiences temporary drawdowns, requiring an investment horizon of at least 5 to 7 years.
13. Capital Gains Taxation Framework
Long-Term Capital Gains (Section 112A): Units held for > 12 months. Gains up to ₹1.25 Lakh per financial year are exempt. Gains above ₹1.25 Lakh are taxed at 12.5%.
Short-Term Capital Gains (Section 111A): Units held for ≤ 12 months. Taxed at flat 20%.
14. Selection Framework: The 3 Criteria
When choosing a Nifty 50 index fund: (1) AUM must exceed ₹3,000 Crore; (2) 3-year tracking error must be under 0.04%; and (3) Direct expense ratio must be under 0.20%. UTI and HDFC comfortably satisfy all three.
15. Pre-Investment SIP Checklist
Recommended Video Tutorials & Practical Walkthroughs
Watch these handpicked, expert video guides covering practical compliance, step-by-step procedures, and real-world implementation:
Recommended Video Tutorials & Practical Guides
16. Frequently Asked Questions (FAQs)
What has been the historical 15-year SIP return of the Nifty 50 TRI index?
Historically over any rolling 15-year investment period between 2005 and 2026, a disciplined monthly SIP in the Nifty 50 Total Return Index (TRI) has generated annualized returns (XIRR) between 12.5% and 14.8%, compounding ₹10,000 monthly investments into ₹65 Lakh to ₹78 Lakh.
Why is Tracking Error more important than past 1-year returns in index funds?
Because index funds are passive clones designed to mirror the benchmark, higher returns than the index actually indicate poor replication. Tracking error measures the volatility of excess returns relative to the benchmark; lower tracking error (ideally under 0.05%) guarantees the fund faithfully replicates the Nifty 50.
What is the typical Direct Plan expense ratio for top Nifty 50 index funds?
Top-tier direct plans like UTI Nifty 50, HDFC Index Nifty 50, and Navi Nifty 50 charge Total Expense Ratios (TER) between 0.06% and 0.20%, compared to 0.75% to 1.80% charged by actively managed large-cap funds.
How are long-term capital gains on Nifty 50 index funds taxed?
Under Section 112A of the Income Tax Act, gains on equity mutual funds held for more than 12 months are classified as LTCG. Gains up to ₹1.25 Lakh per financial year are 100% tax-free; gains exceeding ₹1.25 Lakh are taxed at 12.5% without indexation.
Should an investor choose a Nifty 50 Index Fund or a Nifty 50 ETF?
Index Mutual Funds are ideal for automated monthly SIPs without Demat account requirements, zero brokerage fees, and no bid-ask spread slippage. ETFs require a Demat account and trading terminal, but allow intraday price execution.