
GST on Health & Motor Insurance: Can Your Business Claim 18% ITC?
Every year, Indian companies remit crores in insurance premiums across employee group mediclaim policies, director sedans, and commercial delivery fleets. At a standard 18% GST rate, the tax burden represents almost one-fifth of the entire policy cost.
Can your business set off this 18% GST as Input Tax Credit (ITC), or is it locked under Section 17(5) blocked credits? Here is the complete legal dissection, the statutory employer mandate exception, and an interactive cashflow simulator.
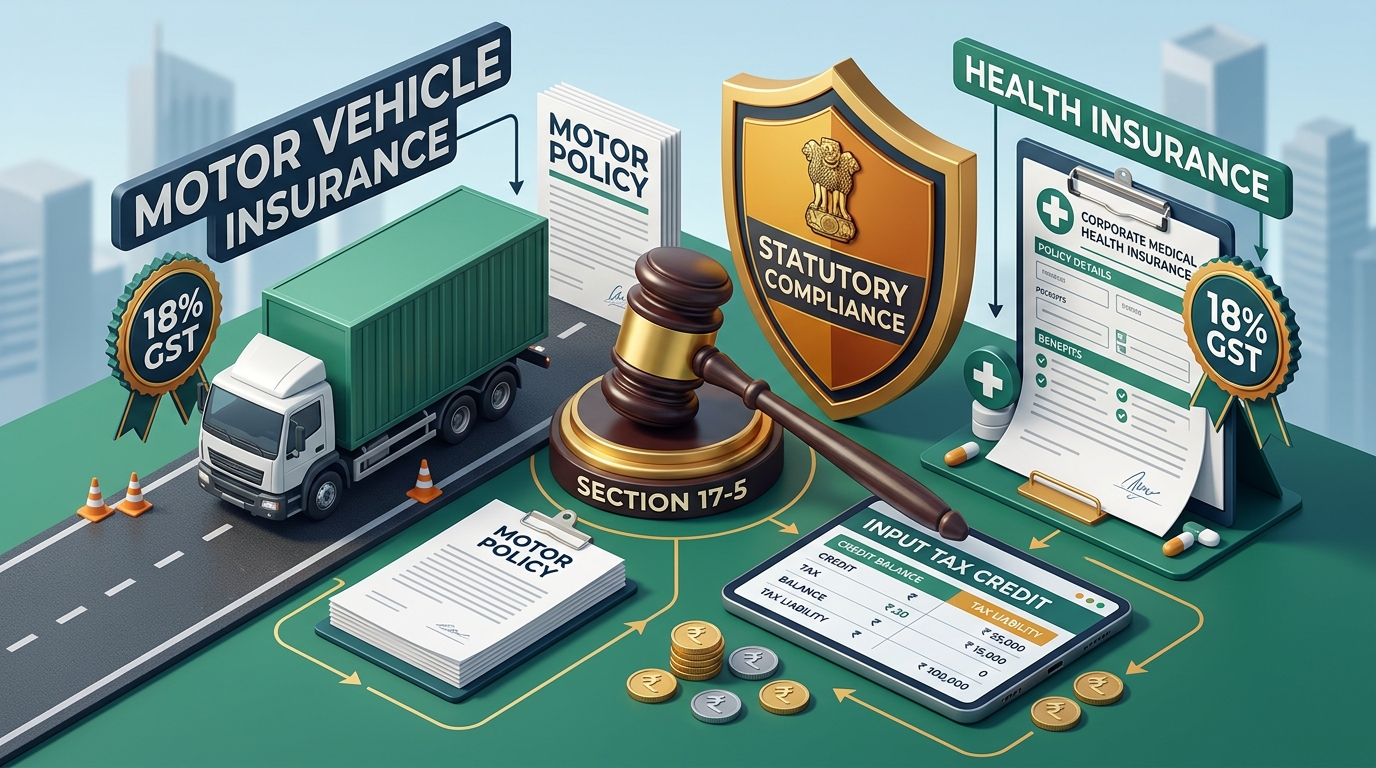
Section 17(5) vs Section 37(1) Bridge
Statutory Exception Analysis & GSTR-3B Reporting Rules
Under Indian GST law, if an insurance policy protects a commercial goods asset (truck, tempo, raw material cargo, factory fire) or is mandated by an Act of Parliament / State Legislature (Factories Act employee health cover), ITC is 100% Eligible. If it covers a passenger car with seating ≤ 13 or voluntary perks without statutory mandate, ITC is Strictly Blocked.
Insurance GST & ITC Claim Eligibility Simulator
Test your policy category against Section 17(5) rules and compute net corporate cashflow savings.
Proviso to Section 17(5)(b): ITC is fully allowed because it is obligatory for the employer to provide health insurance to employees under a statute (e.g. Factories Act 1948 or state factory rules).
1The 18% GST Framework on Insurance Policies in India
In India, insurance services fall under SAC Code 99713 (Life Insurance) and SAC Code 99714 (General Insurance). Almost all commercial and individual policies attract a uniform 18% GST rate:
| Policy Category | SAC Code | GST Rate | General Tax Treatment |
|---|---|---|---|
| Health / Mediclaim (Individual & Group) | 997133 | 18% | Taxable. ITC blocked unless statutory obligation applies. |
| Commercial Goods Motor Vehicles (Trucks / Vans) | 997134 | 18% | Taxable. 100% ITC fully allowable to registered business. |
| Private Passenger Motor Cars (≤13 Seater) | 997134 | 18% | Taxable. ITC blocked under Section 17(5)(a). |
| Factory Fire, Marine Cargo & Transit Risk | 997135 | 18% | Taxable. 100% ITC fully allowable as legitimate business input. |
| Keyman Term Life Policy | 997132 | 18% | Taxable. ITC blocked under Section 17(5)(b)(i). |
2Section 17(5)(b): The Crucial Statutory Exception for Employers
Section 17(5)(b)(i) of the CGST Act explicitly provides that Input Tax Credit shall NOT be available in respect of "food and beverages, outdoor catering, beauty treatment, health services, cosmetic and plastic surgery, life insurance and health insurance".
However, Parliament inserted a vital proviso through the CGST Amendment Act:
"Provided that the input tax credit in respect of such goods or services or both shall be available, where it is obligatory for an employer to provide the same to its employees under any law for the time being in force."
When Employer Health ITC is Allowed
- Factory workers covered under the Factories Act, 1948 or state factory safety notifications.
- Mines, hazardous industrial units, or offshore installations with statutory medical mandates.
- State-specific Shops and Commercial Establishments Acts where employee mediclaim is officially made compulsory.
When Employer Health ITC is Blocked
- Voluntary corporate health perks offered to attract IT/tech employees without statutory obligation.
- Top-up mediclaim coverage above the statutorily mandated limits.
- Individual health policies purchased by directors in company name without legal mandate.
3Motor Vehicle Insurance: Goods Carriers vs Director Passenger Cars
The treatment of motor insurance hinges entirely on vehicle seating capacity and commercial classification under Section 17(5)(a) and 17(5)(ab):
ITC Strictly Blocked. Whether owned by a Private Limited company or used exclusively by the CEO for visiting clients, GST on insurance and repairs cannot be claimed.
100% Eligible ITC. Trucks, delivery vans, tractors, trailers, and logistics fleets carry zero restrictions. All 18% GST paid on insurance is set off in GSTR-3B.
100% Eligible ITC. Busses or staff transport vans with approved seating capacity exceeding 13 persons (e.g. 14, 25, or 50 seaters) qualify for full ITC.
4The Silver Lining: Claiming Blocked GST Under Income Tax Section 37(1)
Many accountants make the mistake of leaving blocked GST in a dormant balance sheet suspense ledger. If Input Tax Credit is legally denied under Section 17(5), you are legally entitled to capitalize that tax into your insurance expense!
Dual Accounting Treatment Matrix:
Base Premium of ₹1,00,000 is debited to Vehicle Insurance Expense (P&L). ₹18,000 is debited to Input CGST/SGST Ledger (Balance Sheet Asset). Full ₹18,000 cash is saved against sales tax liability.
Entire gross amount of ₹1,18,000 (Base ₹1,00,000 + Blocked GST ₹18,000) is debited directly to Vehicle Insurance Expense in P&L. Under Section 37(1), this yields a corporate tax deduction of ₹29,700 (at 25.17%), recovering the vast majority of the tax!
5Exact GSTR-3B Reporting: Table 4(A)(5) vs Table 4(B)(1)
Since the introduction of automated GSTR-2B matching, insurance invoices auto-populate into Table 4(A) of GSTR-3B. Never leave blocked insurance amounts inside Table 4(A):
Retain in Table 4(A)(5) - "All Other ITC". The credit smoothly enters your Electronic Credit Ledger to offset monthly outward tax.
Reclaim and reverse permanently in Table 4(B)(1) - "As per rules 38, 42 and 43 of CGST Rules and section 17(5)". Failing to reverse triggers automated DRC-01A system notices and 18% annual interest under Section 50.
Frequently Asked Questions (FAQ)
Can an employer claim GST Input Tax Credit on Group Health Insurance for employees?
Under Section 17(5)(b)(i) of the CGST Act, ITC on health insurance is generally blocked. However, under the second proviso to Section 17(5)(b), ITC IS 100% ELIGIBLE if providing such health insurance is obligatory for an employer under any law for the time being in force (such as the Factories Act 1948 or state factory rules). If provided voluntarily as a corporate perk without statutory mandate, ITC is blocked.
Can a company claim ITC on insurance for motor cars used by directors or executives?
No. Under Section 17(5)(a) read with Section 17(5)(ab), Input Tax Credit on insurance, servicing, and repair of passenger motor vehicles having approved seating capacity of up to 13 persons is strictly blocked, even if the vehicle is owned by the company and used 100% for official business visits.
Is ITC available on insurance of commercial trucks, delivery tempos, and buses?
Yes, 100% eligible. Commercial goods transport vehicles (trucks, tempos, delivery vans, tractors) do not fall under passenger vehicle restrictions, so full 18% GST ITC is allowed. Similarly, passenger vehicles having an approved seating capacity exceeding 13 persons (such as 20-seater or 40-seater employee transport buses) qualify for full ITC under Section 17(5)(a)(A).
If GST on insurance is blocked under Section 17(5), can it be claimed as an expense under Income Tax?
Yes! Under Section 37(1) of the Income Tax Act 1961, any non-refundable tax incurred wholly and exclusively for business purposes is deductible as a revenue expenditure. When GST ITC is legally blocked under Section 17(5), the 18% GST portion is added to the insurance expense in your P&L statement, providing a corporate tax deduction of 25.17% or 31.2% on the combined premium plus tax.
Where should blocked insurance ITC be reported in GSTR-3B return?
Ineligible insurance ITC must be reported in Table 4(B)(1) ("As per section 17(5)") or Table 4(D)(1) depending on whether the invoice was initially auto-drafted into Table 4(A) from GSTR-2B. This ensures permanent reversal without affecting your Electronic Credit Ledger balances.
Recommended Video Tutorials & Practical Walkthroughs
Watch these handpicked, expert video guides covering practical compliance, step-by-step procedures, and real-world implementation:
Recommended Video Tutorials & Practical Guides
Stop Losing Cash on Misclassified ITC & Section 17(5) Notices
GST Munshi automatically classifies your purchase registers, isolates Section 17(5) blocked credits, reconciles monthly GSTR-2B statements, and generates error-free GSTR-3B summaries in seconds.