
SVAMITVA Scheme: Rural Property Cards, Drone Mapping & Bank Loans Guide
Quick Summary & Key Takeaways (Featured Snippet)
1. Statutory Overview: Ministry of Panchayati Raj SVAMITVA Framework & Historical Land Rights Void
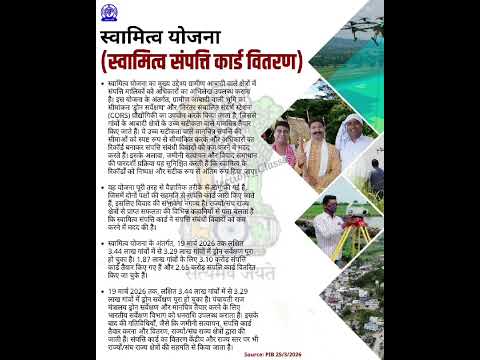
In India's comprehensive socioeconomic and industrial policy landscape, government schemes, financial subsidies, and asset formalization programs represent vital economic growth drivers. SVAMITVA Scheme: Rural Property Cards, Drone Mapping & Bank Loans Guide serves as a foundational guide for entrepreneurs, farmers, industrial developers, and citizens seeking to leverage sovereign incentives and capital assistance.
Policy Framework & National Strategic Objectives
Spearheaded by Central Ministries, State Governments, and specialized development agencies, these flagship programs aim to formalize legal rights, enhance productivity, boost exports, and unlock institutional banking credit for sustainable national wealth creation.
2. The 'Abadi' Land Dilemma: Why Rural Residential Properties Lacked Legal Title Deeds for Centuries
Accessing sovereign benefits requires fulfilling rigorous statutory criteria and technical milestones. Program guidelines establish transparent eligibility parameters and legal safeguards to ensure targeted benefit delivery.
Beneficiary Rights & Entitlements
Statutory capital subsidies, interest subvention discounts, sovereign credit guarantee covers, and formal legal title ownership.
Technical Conditions & Thresholds
Mandatory minimum capital expenditure, physical asset verification, boundary dispute resolution, and strict domestic manufacturing norms.
3. Survey Technology: High-Resolution Drone Mapping & Continuously Operating Reference Stations (CORS)
Detailed project reports (DPR), audited financial models, land possession records, and technical compliance certificates constitute the critical evidentiary dossier required by sanctioning committees.
4. Ground-Truthing Protocols: 'Chuna' Demarcation, Joint Field Verification & Gram Sabha Meetings
The governance architecture spans District Level Committees (DLC), State Level Approval Committees (SLAC), Project Management Agencies, and Central Ministries operating through digital single-window portals.
5. Public Objection Mechanism: Gram Panchayat Hearing & Sub-Divisional Magistrate (SDM) Appeals
Statutory timelines, implementation milestones, public objection windows, and periodic claim filing schedules must be tracked with absolute diligence to prevent disqualification or forfeiture of sovereign aid.
6. Issuance of Property Cards: State Nomenclature (Gharoni, Sampatti Patra, Sanad) & Legal Standing
Financial structuring, combining term loan debt from commercial banks with capital subsidies, interest subvention, and promoter equity, significantly reduces weighted average cost of capital (WACC) and accelerates project return on investment (ROI).
7. Bank Collateralization SOP: Mortgaging SVAMITVA Property Cards for Commercial & MSME Loans
Beneficiaries must maintain rigorous post-sanction compliance, ensuring that assets are not alienated, production milestones are sustained, and statutory accounts are audited by authorized agencies.
8. Step-by-Step SOP: From Drone Flight Over Village to Receiving Stamped Property Card
Project Conceptualization & Eligibility Pre-Screening
Confirm scheme eligibility, land title availability, technology specifications, and prepare an exhaustive Detailed Project Report (DPR).
Online Digital Portal Registration & Submission
Register on the official government single-window portal, upload required land records, technical DPRs, and bank consent letters.
Technical Scrutiny & Sanction Order Issuance
Navigate scrutiny by designated district and state appraisal committees to obtain the formal Administrative Sanction Order.
Implementation, Physical Audit & DBT Disbursement
Complete asset installation, undergo physical inspection by authorized verification officers, and receive electronic direct benefit transfer.
9. Comparative Matrix: Traditional Khasra/Khatauni (Agricultural) vs SVAMITVA Property Card (Abadi)
| Program Parameter | Sovereign Flagship Scheme | Conventional Banking / Market Route | Unsubsidized / Informal Method |
|---|---|---|---|
| Financial Subsidy / Aid | 30% to 60% Capital Grant | Zero Subsidy | 100% Out-of-Pocket Cost |
| Interest Rate / Cost | 3% Subvention / Capped Rates | Standard Commercial Rates | High Informal Borrowing Rates |
| Collateral / Security | CGTMSE Free Cover / Legal Title | 100% Physical Mortgage | Unsecured / Disputed Rights |
| Institutional Validation | Official Central/State Sanction | Commercial Credit Rating | Unrecognized |
10. Real-World Case Study: Farmer Secures ₹12 Lakh SBI MSME Loan Against Newly Issued Gharoni
Socioeconomic Case Study: Unlocking Sovereign Value
An ambitious entrepreneurial enterprise successfully leveraged government programs to establish modern infrastructure and expand commercial capacity.
The project faced heavy upfront capital requirements, high commercial borrowing interest rates, and complex land documentation challenges.
Through structured portal filings and inter-agency scheme convergence, the promoter secured substantial capital subsidy, reduced debt service costs, and achieved commercial operational stability.
11. High-Risk Scrutiny Pitfalls: Family Partition Disputes, Encroachments & Succession Updating
Common pitfalls during scheme execution include defective DPR submissions, failure to establish undisputed land possession, ignoring domestic component mandates, and submitting fraudulent invoices. Adhering to verified statutory guidelines ensures seamless approval.
12. Empowerment of Local Bodies: Gram Panchayat Property Tax Assessment & Spatial GIS Planning
The strategic convergence between Central sector schemes, State industrial policies, and bank priority sector lending creates an unparalleled multiplier effect for regional economic empowerment.
13. Synergy with DILRMP: Integration with Digital India Land Records Modernization Programme
Statutory guidelines and administrative circulars issued by Central Ministries establish legally binding obligations on implementing agencies, guaranteeing fair and transparent processing of citizen applications.
14. Decision Matrix: Agricultural Land Collateral vs SVAMITVA Abadi Property Collateral
Promoters and beneficiaries must conduct careful feasibility modeling, aligning their operational expansion plans with the specific eligibility parameters and disbursement milestones of respective government schemes.
15. Rural Property Owner's SVAMITVA Verification & Bank Loan Readiness Checklist
Recommended Video Tutorials & Practical Walkthroughs
Watch these handpicked, expert video guides covering practical compliance, step-by-step procedures, and real-world implementation:
Recommended Video Tutorials & Practical Guides
16. Frequently Asked Questions (FAQs)
17. Ministry Guidelines, State Revenue Codes & Survey of India Technical Manuals Compendium
SVAMITVA Scheme Guidelines (Ministry of Panchayati Raj, Government of India, 2020); Survey of India Technical Manual on Drone Surveys and CORS Network; State Revenue Codes (e.g. UP Revenue Code 2006, MP Land Revenue Code 1959); Transfer of Property Act, 1882 (Section 58 Mortgages).