What are the real interest rates, salary eligibility, and CIBIL score for a Moneyview loan?
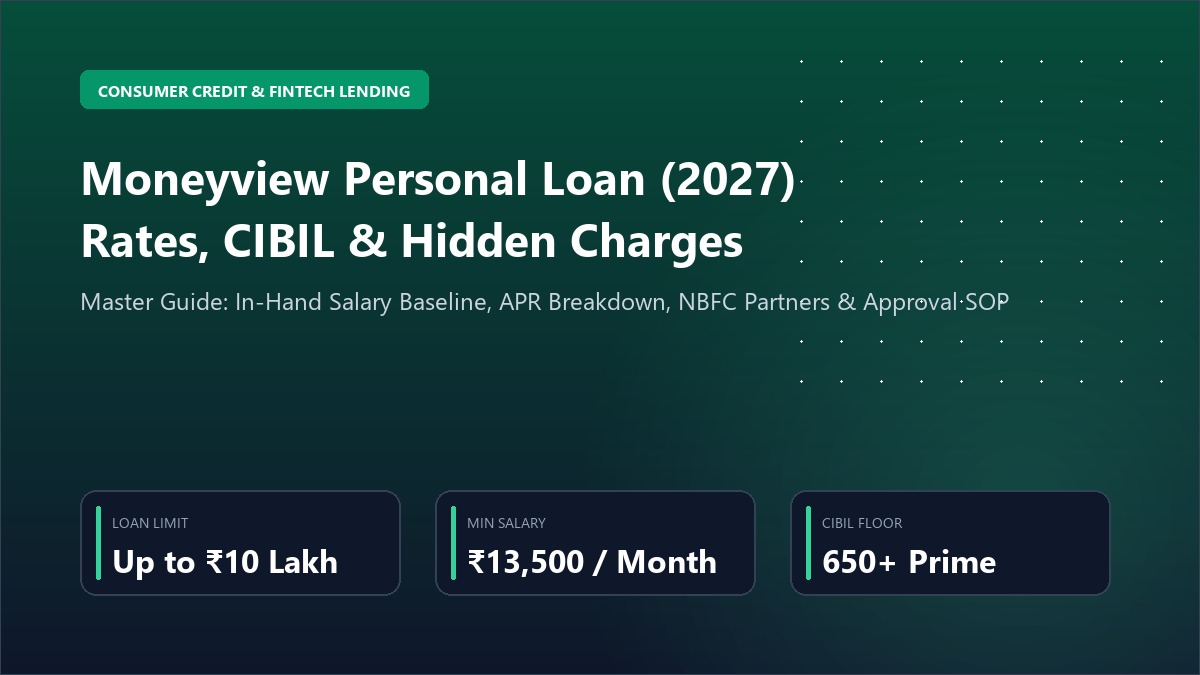
Moneyview offers unsecured personal loans from ₹5,000 to ₹10,00,000 with repayment tenures of 3 to 60 months. Quoted annual interest rates start at 1.33% per month (16% p.a.) for prime borrowers and scale up to 36% p.a. for elevated-risk profiles. The minimum monthly in-hand salary requirement is ₹13,500 for salaried employees (credited via bank transfer) and a baseline CIBIL score of 650+. An upfront processing fee of 2% to 7% (+18% GST) is deducted directly from the approved loan before bank disbursement.
1. Interactive Moneyview EMI & Effective Annualized APR Calculator
Because processing fees and GST are deducted upfront from your loan, the real borrowing cost (APR) is higher than the nominal rate. Use this calculator to audit your exact net cash credit and monthly EMI:
Moneyview True EMI & Effective Annualized APR Calculator (2027)
Calculates real monthly installments, upfront GST deductions, net bank credit, and effective borrowing cost
2. Moneyview's RBI-Registered Lending Partner Network
Under the RBI Digital Lending Guidelines (RBI/2022-23/111), lending apps must explicitly disclose the underlying regulated balance sheet providing the capital. Moneyview acts as a Lending Service Provider (LSP), originating loans through certified NBFC partners:
Moneyview’s captive RBI-registered Non-Banking Financial Company (Registration No. N-02.00287). Captures prime salaried applications with rapid algorithmic sanctioning.
- DMI Finance Pvt Ltd: Large-ticket personal credit and Tier-1 urban underwriting.
- Aditya Birla Finance Ltd: High-ticket enterprise salaried loans up to ₹10 Lakhs.
- SMFG India Credit (Fullerton): Broad risk appetite covering self-employed and MSME borrowers.
- Northern Arc Capital & Vivriti Capital: Structured consumer debt and alternate data portfolios.
3. Detailed Eligibility Criteria: In-Hand Salary & CIBIL Thresholds
Moneyview utilizes algorithmic underwriting that rejects unqualified applications instantly without human intervention. Ensure you satisfy all four statutory conditions:
| Parameter | Salaried Applicants | Self-Employed / MSME | Mandatory Rejection Trigger |
|---|---|---|---|
| Minimum In-Hand Income | ₹13,500 / month (Metro ₹15k) | ₹15,000 / month net turnover | Cash salary or Third-Party UPI deposits |
| Mode of Salary Credit | Direct Bank NEFT / RTGS / IMPS | Current / Savings Business Account | Cash deposit in ATM / Cash voucher |
| CIBIL / Experian Score | 650+ (Prime 700+ for best rates) | 675+ with 1+ year vintage | Recent default, DPD > 30, or Write-Off status |
| Age Requirement | 21 to 57 Years | 23 to 59 Years | Age < 21 or > 60 at loan maturity |
4. Complete Fee Schedule, Foreclosure Penalties & Late Fees
In compliance with the Key Fact Statement (KFS) mandate under RBI guidelines, all fees must be transparently disclosed:
Between 2.0% and 7.0% of sanctioned principal plus 18% GST. Example: On a ₹2,00,000 loan at 3% fee, ₹6,000 + ₹1,080 GST (₹7,080 total) is deducted, disbursing ₹1,92,920.
Borrowers must serve a lock-in period of minimum 3 paid EMIs. For floating-rate individual loans, the RBI mandates zero foreclosure penalty. For fixed-rate personal loans, partner NBFCs may charge 0%–3%.
If an auto-debit bounces due to insufficient balance, a penalty of ₹500 per bounce is levied, plus penal interest of 2% to 3% per month on the overdue installment.
5. Step-by-Step SOP: Applying for a Moneyview Loan with Instant Approval
Follow this 4-step verified workflow to prevent verification bottlenecks and secure same-day disbursement:
Enter your PAN number, date of birth, and employment details. Complete instant Aadhaar biometric OTP verification via Digilocker. Ensure the mobile number linked to Aadhaar is active to receive the 6-digit UIDAI OTP.
Authenticate via the RBI-regulated Account Aggregator (AA) framework using your Net Banking or mobile OTP. This securely parses 3 months of bank statements without requiring physical document scanning.
Authorize automated monthly EMI deductions using your Debit Card or Net Banking credentials via NPCI e-Mandate. Select an EMI debit date matching your monthly salary credit cycle (e.g. 5th of each month).
Review the statutory Key Fact Statement (KFS) confirming the net disbursed sum, total interest, and APR. Sign the agreement digitally via Aadhaar e-Sign OTP. Funds are disbursed via NEFT/IMPS within 2 to 24 hours.
6. How to Recover If Your Moneyview Loan Application Was Rejected
If an application is rejected, Moneyview imposes a strict 90-day cooling-off window. Do not re-apply immediately across multiple lending apps (KreditBee, Navi, Cashe); rapid hard inquiries reduce your credit score by 15–30 points.
The algorithm rejects bank statements showing: (a) multiple gambling/betting transactions, (b) ongoing high UPI micro-borrowings, or (c) negative monthly ending balances. Maintain an average monthly balance of at least 15% of your salary for 90 days before re-applying.
7. Verified Video Tutorials: Application Process & Approval Proof
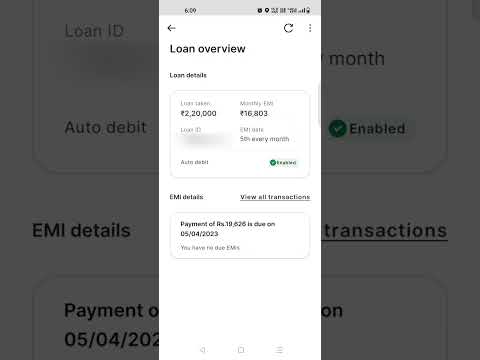
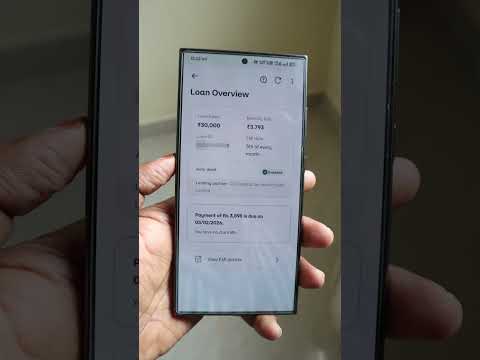
Watch real borrowers walk through the Moneyview application process, document uploading, and live bank credit confirmation:
8. Frequently Asked Questions (FAQ)
Does checking my loan offer on Moneyview hurt my CIBIL score?
Checking your pre-approved eligibility or loan offer on Moneyview performs a Soft Credit Pull, which does NOT impact your credit score. A Hard Credit Inquiry (which temporarily lowers your score by 2–5 points) is logged on your bureau only when you accept the loan offer and proceed to final digital agreement signing.
Can I get a loan without salary slips or ITR on Moneyview?
Yes. Physical salary slips and Income Tax Returns (ITR) are optional for loan amounts up to ₹3,00,000 if your bank account is verified via the RBI Account Aggregator (AA) network or by uploading a 3-month PDF bank statement that reflects regular monthly salary credits.
What should I do if Moneyview debits my EMI twice in the same month?
Double debit usually happens if an e-NACH auto-debit and a manual in-app payment cross paths. Raise a grievance ticket directly in the app under Help > Payments Issue with the UTR transaction number. Under RBI digital lending directives, excess debited amounts must be refunded to your original bank account within 3 to 5 business days.