Which are the top credit cards in India in 2027?
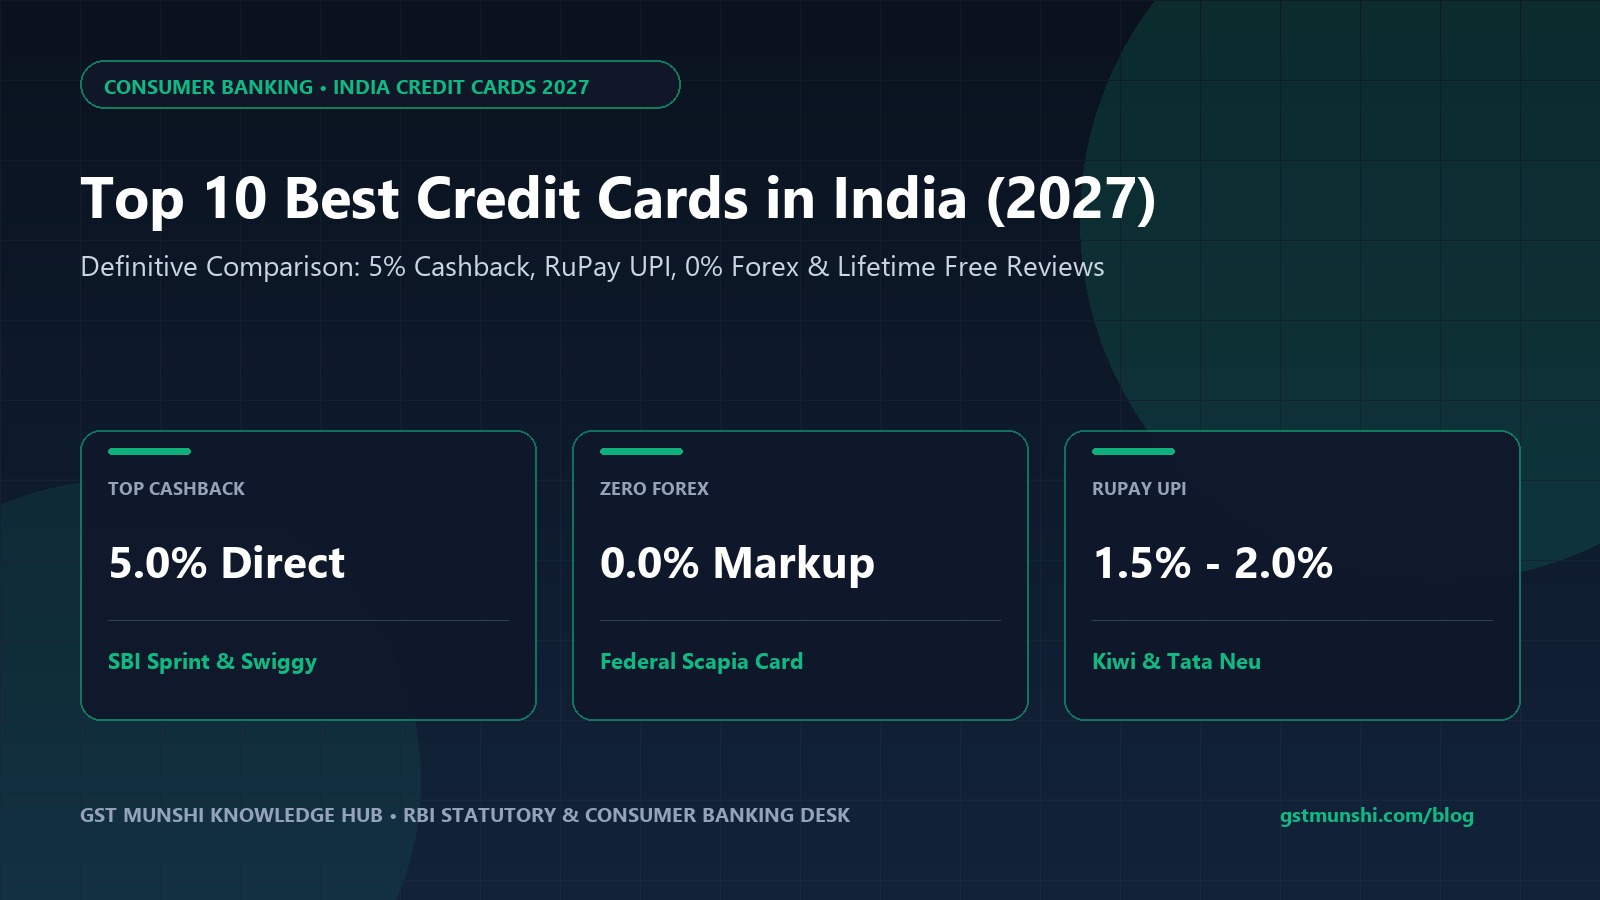
The SBI Cashback Credit Card is India's #1 card for online shopping, delivering a flat 5% direct statement cashback on virtually all online platforms (up to ₹5,000/month). For food and groceries, the HDFC Swiggy Credit Card leads with 10% cashback. For international travel, the Federal Bank Scapia Card provides 0% foreign exchange markup and lifetime-free status. For UPI merchant QR payments, the Tata Neu Infinity and Kiwi Virtual RuPay cards grant 1.5% to 2.0% return on daily local spending.
Credit Card Annual Net Benefit & Cashback Estimator
Adjust your estimated monthly spending to dynamically discover your highest-yielding card after annual fees.
#1 Top Recommended Card
HDFC Swiggy Credit Card
Net Profit: +₹24,264/yr
| Rank & Card | Gross Rewards | Net Fee Applied | Net Annual Savings |
|---|---|---|---|
| 1HDFC Swiggy Credit Card | ₹24,264 | ₹0 (Waived) | +₹24,264 |
| 2Tata Neu Infinity HDFC Credit Card | ₹23,298 | ₹0 (Waived) | +₹23,298 |
| 3Airtel Axis Bank Credit Card | ₹16,080 | ₹0 (Waived) | +₹16,080 |
| 4SBI Cashback Credit Card (Sprint) | ₹12,600 | ₹0 (Waived) | +₹12,600 |
| 5AU LIT Customizable Credit Card | ₹10,800 | ₹0 (Waived) | +₹10,800 |
Top 10 Credit Cards in India (2027 Master Matrix)
Side-by-side benchmark comparing annual fees, fee waiver spend criteria, key reward rates, and direct application links.
| Card Name & Issuer | Category USP | Annual Fee | Fee Waiver Spend | Core Reward Rate | Lounge Access | Direct Apply |
|---|---|---|---|---|---|---|
| State Bank of India (SBI Cards) | #1 Online Shopping | ₹999 + 18% GST | ₹2,00,000 / year | Flat 5% Cashback on ALL online spends (Amazon, Flipkart, Myntra, etc.) | No complimentary lounge visits | Apply |
| HDFC Bank | 10% Food & Dining | ₹500 + 18% GST | ₹2,00,000 / year | 10% Cashback on Swiggy (Food, Instamart, Dineout) + 5% on 1,000+ top apps | No complimentary lounge visits | Apply |
| Federal Bank (Fintech Co-Branded) | 0% Forex Travel | ₹0 (Lifetime Free) | No spend criteria (Always Free) | 0.0% Zero Forex Markup + 10% to 20% Scapia Coins on all domestic/international spends | Unlimited Domestic Airport Lounge Access (on spending ₹5,000 in preceding cycle) | Apply |
| HDFC Bank (Tata Digital Co-Branded) | 10% Tata + RuPay UPI | ₹1,499 + 18% GST | ₹3,00,000 / year | 10% NeuCoins on Tata Neu ecosystem + 1.5% NeuCoins on RuPay UPI merchant spends | 8 Domestic Airport Lounges/yr (2/qtr) + 4 International via Priority Pass | Apply |
| Axis Bank (Airtel Co-Branded) | 25% Telecom & 10% Utilities | ₹500 + 18% GST | ₹2,00,000 / year | 25% on Airtel Recharges + 10% on Utilities (Electricity, Gas) + 10% on Swiggy/Zomato | 4 Domestic Airport Lounge Visits per year | Apply |
| IDFC FIRST Bank | 100% Lifetime Free | ₹0 (Lifetime Free Forever) | No spend criteria (Always Free) | 10X Rewards on incremental spends above ₹20k + Dynamic APR from 9% p.a. | 4 Railway Lounges/qtr + 4 Airport Lounges/qtr (on ₹20k monthly spend) | Apply |
| AU Small Finance Bank | Build Your Own Card | ₹0 (Pay only for feature packs you activate) | No spend criteria on base card | Custom on-demand 5% cashback packs, 10X reward boosts, and lounge packages via app | 4 Airport Lounge visits per 90-day pack (activated via AU 0101 app) | Apply |
| Axis Bank Engine (Kiwi Fintech Co-Branded) | 1.5% RuPay UPI Cash | ₹0 (Virtual Lifetime Free) | No spend criteria (Always Free) | Flat 1.5% to 2.0% direct cash rewards (Kiwis) on scan-and-pay merchant UPI transactions | No complimentary lounge visits | Apply |
| Bank of Baroda (BOB Financial) | 5X Travel & Dining | ₹1,000 + 18% GST | ₹1,20,000 / year (Lowest in Category) | 5X Rewards (10 points per ₹100 = 2.5% value) on Travel, Dining, and Overseas Spends | 4 Complimentary Domestic Airport Lounge Visits per year (1/quarter) | Apply |
| Scheduled Commercial Bank Engine (Credilio Co-Branded) | 100% Guaranteed Approval | ₹0 (Lifetime Free) | No spend criteria (Always Free) | Earn 7.0%+ FD Interest on Deposit + 100% Approval with Zero CIBIL Check | No complimentary lounge visits | Apply |
SBI Cashback Credit Card (Sprint)
Issued by State Bank of India (SBI Cards) • Optimized for Heavy online shoppers seeking direct, hassle-free statement credits without merchant lock-in.
Joining Fee
₹999 + 18% GST
Annual Renewal Fee
₹999 + 18% GST
Fee Waiver Condition
₹2,00,000 / year
Airport Lounge Access
No complimentary lounge visits
Key Advantages & Standout Features
- Unmatched flat 5% direct cashback on nearly all online shopping merchants with no merchant restriction.
- Cashback is credited automatically to your credit card statement 2 days prior to next billing date.
- High monthly cashback ceiling of ₹5,000 per billing cycle (requires ₹1,00,000 monthly online spend to max out).
- Low annual fee waiver milestone of ₹2,00,000, easily achievable by regular households.
- 1% cashback on all offline merchant retail spends with zero minimum threshold.
Limitations & Exclusions to Note
- Zero airport lounge access included (discontinued to preserve the 5% cashback economics).
- Excluded categories from 5% rate: Rent, wallet loads, school fees, utilities, and jewellery.
- No fuel surcharge waiver available on this specific card variant.
- Joining fee of ₹999 + GST applies in the first year without welcome gift vouchers.
Age: 21 – 60 Years
Income: ₹30,000/month (Salaried) or ₹3.6 Lakh ITR (Self-Employed)
Min CIBIL: 750+ Recommended
“SBI Cashback remains the king of retail cards in India. I earn ₹3,500 to ₹4,500 in direct statement reductions every single month without converting points or booking unwanted flights.”
HDFC Swiggy Credit Card
Issued by HDFC Bank • Optimized for Foodies, bachelors, and families spending heavily on Swiggy Food, Instamart, and Dineout.
Joining Fee
₹500 + 18% GST
Annual Renewal Fee
₹500 + 18% GST
Fee Waiver Condition
₹2,00,000 / year
Airport Lounge Access
No complimentary lounge visits
Key Advantages & Standout Features
- Industry-leading 10% cashback on all Swiggy services (Food Delivery, Instamart groceries, Dineout, Genie).
- 5% cashback across 1,000+ top digital partner merchants including Amazon, Flipkart, Nike, Nykaa, and Uber.
- Includes complimentary 3-month Swiggy One membership worth ₹1,199 as a welcome gift.
- Low annual fee of just ₹500 + GST, easily covered within the first month of regular food orders.
- Issued on Mastercard or RuPay platform, enabling seamless digital transactions.
Limitations & Exclusions to Note
- Cashback is credited as Swiggy Money inside the Swiggy App wallet rather than direct cash into your bank account.
- Category sub-caps apply: Maximum ₹1,500/month for 10% Swiggy spends and ₹1,500/month for 5% partner apps.
- No complimentary domestic airport lounge visits.
- Excluded categories: Fuel, rent payments, wallet top-ups, and government transactions.
Age: 21 – 60 Years
Income: ₹25,000/month (Salaried) or ₹3.0 Lakh ITR (Self-Employed)
Min CIBIL: 730+
“For metro households ordering groceries on Instamart 3 times a week and ordering dinner twice a weekend, HDFC Swiggy saves over ₹1,200 every month like clockwork.”
Federal Bank Scapia Credit Card
Issued by Federal Bank (Fintech Co-Branded) • Optimized for International travelers, foreign students, and cross-border SaaS/e-commerce shoppers.
Joining Fee
₹0 (Lifetime Free)
Annual Renewal Fee
₹0 (Lifetime Free)
Fee Waiver Condition
No spend criteria (Always Free)
Airport Lounge Access
Unlimited Domestic Airport Lounge Access (on spending ₹5,000 in preceding cycle)
Key Advantages & Standout Features
- True 0.0% zero foreign exchange markup on all international card swipes and cross-border online payments.
- 100% Lifetime Free with zero joining fee and zero annual recurring charges forever.
- Unlimited domestic airport lounge access across India with the lowest spend barrier in the country (just ₹5,000).
- Earn 10% Scapia Coins (5 coins per ₹100 = 1% value) on domestic spends and 20% coins (4% value) on travel bookings.
- Instant 100% paperless onboarding on the Scapia mobile application in under 5 minutes.
Limitations & Exclusions to Note
- Federal Bank co-branded policy restrictions: Users already holding a Federal Bank co-branded card may face approval limits.
- Scapia Coins can only be redeemed for flight and hotel bookings inside the Scapia travel portal.
- No physical statement credit cash option; strictly travel-oriented redemption.
- Customer support is entirely app-chat based without dedicated physical branch desk support.
Age: 23 – 60 Years
Income: ₹30,000/month or regular filed ITR
Min CIBIL: 750+
“Scapia saved me ₹22,000 in forex conversion fees during my 3-week trip to Japan and Singapore. The ₹5,000 domestic lounge qualification is ridiculously easy compared to other banks requiring ₹50,000.”
Tata Neu Infinity HDFC Credit Card
Issued by HDFC Bank (Tata Digital Co-Branded) • Optimized for Shoppers frequently using BigBasket, 1mg, Croma, Air India, Taj Hotels, and daily RuPay UPI.
Joining Fee
₹1,499 + 18% GST
Annual Renewal Fee
₹1,499 + 18% GST
Fee Waiver Condition
₹3,00,000 / year
Airport Lounge Access
8 Domestic Airport Lounges/yr (2/qtr) + 4 International via Priority Pass
Key Advantages & Standout Features
- Industry-leading 1.5% NeuCoins on all RuPay UPI merchant QR payments (1 NeuCoin = ₹1 cash value).
- Up to 10% NeuCoins return on purchases made on the Tata Neu app (5% NeuPass + 5% card reward).
- Welcome bonus of 1,499 NeuCoins credited upon paying the joining fee and completing the first spend.
- Comprehensive airport lounge suite: 8 complimentary domestic visits plus 4 international visits via Priority Pass.
- NeuCoins can be spent 1:1 like real cash across BigBasket, Croma, Air India, Tata CliQ, and Taj Hotels.
Limitations & Exclusions to Note
- Annual fee of ₹1,499 is higher than standard entry-level cashback cards.
- Maximum reward velocity is tied to the Tata brand ecosystem; spends outside Tata earn standard 1.5%.
- Fee waiver threshold is ₹3,00,000 per year, which may be steep for budget spenders.
- UPI cashback is strictly applicable on merchant QR codes; peer-to-peer (P2P) transfers are excluded.
Age: 21 – 65 Years
Income: ₹50,000/month (Salaried) or ₹6.0 Lakh ITR (Self-Employed)
Min CIBIL: 750+
“The Tata Neu Infinity RuPay card completely changed how I pay for groceries. Paying via RuPay UPI on BigBasket earns me 10% NeuCoins, which I use to offset my next month's pharmacy bill on 1mg.”
Airtel Axis Bank Credit Card
Issued by Axis Bank (Airtel Co-Branded) • Optimized for Households paying monthly mobile, broadband, DTH, electricity, water, and gas bills.
Joining Fee
₹500 + 18% GST
Annual Renewal Fee
₹500 + 18% GST
Fee Waiver Condition
₹2,00,000 / year
Airport Lounge Access
4 Domestic Airport Lounge Visits per year
Key Advantages & Standout Features
- Staggering 25% cashback on Airtel Mobile, Broadband, and DTH recharges via the Airtel Thanks App.
- 10% cashback on essential utility bill payments (Electricity, Water, Gas, LPG cylinders) via Airtel Thanks.
- 10% cashback on preferred lifestyle delivery platforms: Swiggy, Zomato, and BigBasket.
- Cashback is credited as a direct statement credit on your next credit card billing cycle.
- Includes 4 complimentary domestic airport lounge visits per calendar year.
Limitations & Exclusions to Note
- Monthly cashback capping applies: Maximum ₹250/month on Airtel bills, ₹250/month on utilities, and ₹500/month on food.
- Optimal value is restricted to consumers using Airtel mobile or fiber connections.
- Utility cashback requires payments to be routed exclusively through the Airtel Thanks payment interface.
- Fuel spends, wallet loads, rent, and educational institution payments do not earn reward points.
Age: 21 – 65 Years
Income: ₹25,000/month (Salaried) or ₹3.0 Lakh ITR (Self-Employed)
Min CIBIL: 740+
“Every Indian household has electricity and broadband bills. This single card refunds ₹500 every month on essential utilities and another ₹500 on Swiggy. That is ₹12,000 net savings annually for a ₹500 card.”
IDFC FIRST Classic / Select Credit Card
Issued by IDFC FIRST Bank • Optimized for Salaried individuals and professionals seeking a transparent, permanent zero-fee card with low APR.
Joining Fee
₹0 (Lifetime Free Forever)
Annual Renewal Fee
₹0 (Lifetime Free Forever)
Fee Waiver Condition
No spend criteria (Always Free)
Airport Lounge Access
4 Railway Lounges/qtr + 4 Airport Lounges/qtr (on ₹20k monthly spend)
Key Advantages & Standout Features
- 100% Lifetime Free with absolutely zero joining fees and zero annual maintenance fees forever.
- Reward points NEVER expire and can be redeemed instantly for statement cash without catalog fees.
- Low dynamic interest rates (APR) ranging from 9.0% to 36% p.a., compared to 42% on other private banks.
- Interest-free cash withdrawal from ATMs across India for up to 48 days (only nominal ₹199 fee applies).
- Complimentary railway lounge access across major Indian railway hubs without spend conditions.
Limitations & Exclusions to Note
- Base reward rate for spends under ₹20,000 per month is modest (3X points = ~0.75% value back).
- Complimentary domestic airport lounge access now requires ₹20,000 minimum spend in the previous month.
- Forex markup fee is 3.5% + GST on the Classic variant (Select variant is 1.99%).
- High reward accelerators (10X) trigger only after crossing ₹20,000 in monthly spends.
Age: 21 – 65 Years
Income: ₹25,000/month or existing clean banking relationship
Min CIBIL: 730+
“IDFC FIRST cards are the gold standard for zero-maintenance peace of mind. No hidden annual charges, points that never expire, and railway lounge access that actually works on weekend trips.”
AU LIT Customizable Credit Card
Issued by AU Small Finance Bank • Optimized for Tech-savvy cardholders who want full control to switch perks ON and OFF based on their schedule.
Joining Fee
₹0 (Lifetime Free Base)
Annual Renewal Fee
₹0 (Pay only for feature packs you activate)
Fee Waiver Condition
No spend criteria on base card
Airport Lounge Access
4 Airport Lounge visits per 90-day pack (activated via AU 0101 app)
Key Advantages & Standout Features
- India's first customizable credit card: Activate only the perks you need (dining, travel, groceries) via the AU 0101 app.
- Zero fixed annual fee: The base card is 100% Lifetime Free; pay nominal micro-fees only for activated packs.
- High reward potential: 5% cashback packs on travel or dining can be toggled on during vacation seasons.
- Complimentary airport lounge access packages can be activated for 90 days prior to domestic travel.
- Generous reward accelerator packs yielding up to 10X reward points on online shopping.
Limitations & Exclusions to Note
- Requires proactive management: Feature packs expire after 90 days and must be manually renewed.
- If you forget to activate feature packs, the base card yields a standard low reward rate of 1 point per ₹100.
- AU Small Finance Bank branch presence is concentrated primarily in North, West, and Central India.
- Feature pack subscription fees are non-refundable even if you do not spend enough to utilize them.
Age: 21 – 60 Years
Income: ₹25,000/month (Salaried) or ₹3.0 Lakh ITR (Self-Employed)
Min CIBIL: 740+
“When traveling in October and November, I turn on the 5% travel cashback and airport lounge pack on the AU app for ₹299. For the rest of the year, the card sits at zero cost in my wallet.”
Kiwi Virtual RuPay UPI Credit Card
Issued by Axis Bank Engine (Kiwi Fintech Co-Branded) • Optimized for Daily micro-spenders who pay local shops, grocers, pharmacies, and street vendors via UPI QR codes.
Joining Fee
₹0 (Virtual Lifetime Free)
Annual Renewal Fee
₹0 (Virtual Lifetime Free)
Fee Waiver Condition
No spend criteria (Always Free)
Airport Lounge Access
No complimentary lounge visits
Key Advantages & Standout Features
- Instant 60-second virtual issuance directly inside the Kiwi app with zero paperwork or physical courier wait.
- Earn flat 1.5% to 2.0% cash rewards ('Kiwis') on all merchant UPI payments (2 Kiwis = ₹1 direct bank cash).
- Cashback is credited directly to your primary bank savings account via UPI; no voucher redemption hoops.
- Seamless phone camera scan-and-pay: Works effortlessly on BharatPe, Paytm, PhonePe, and Google Pay merchant QRs.
- 100% Lifetime Free with zero annual recurring charges or hidden renewal criteria.
Limitations & Exclusions to Note
- Virtual-only card: Does not include a physical plastic chip card for offline point-of-sale (POS) machine swipes.
- Peer-to-peer (P2P) transfers to friends, family, or individual phone numbers earn zero rewards.
- Monthly reward capping applies to prevent commercial transaction abuse on personal accounts.
- Cannot be used for physical contactless tap-and-pay at terminals that do not display UPI QR codes.
Age: 21 – 55 Years
Income: ₹20,000/month or existing UPI credit score profile
Min CIBIL: 720+
“Paying for daily chai, petrol, and grocery shopping using Kiwi's RuPay UPI card earned me ₹850 in direct bank cash last month. It turns everyday small QR payments into guaranteed money.”
Bank of Baroda Premier Credit Card
Issued by Bank of Baroda (BOB Financial) • Optimized for Conservative spenders and families seeking PSU bank stability with high dining/travel rewards.
Joining Fee
₹1,000 + 18% GST (Waived on ₹10k spend in 60d)
Annual Renewal Fee
₹1,000 + 18% GST
Fee Waiver Condition
₹1,20,000 / year (Lowest in Category)
Airport Lounge Access
4 Complimentary Domestic Airport Lounge Visits per year (1/quarter)
Key Advantages & Standout Features
- Extremely low annual fee waiver milestone: Spend just ₹1,20,000 annually (₹10,000/month) to waive renewal fee.
- 5X Reward Points on travel, dining, and international transactions, delivering a competitive 2.5% reward rate.
- Complimentary domestic airport lounge access across major Indian terminals (1 visit per quarter).
- 1% fuel surcharge waiver across all fuel stations in India for transactions between ₹400 and ₹5,000.
- Public Sector Bank (PSU) backing guarantees transparent billing and absence of predatory billing practices.
Limitations & Exclusions to Note
- BOB Financial mobile app and web portal user experience is basic compared to modern private fintechs.
- Reward redemption requires paying a nominal catalog processing charge of ₹99 + GST.
- Customer service response turnaround times can be slower than top private sector card issuers.
- Foreign currency markup is 3.5% + GST, making it uncompetitive for international swipes compared to Scapia.
Age: 21 – 65 Years
Income: ₹30,000/month (Salaried) or ₹3.6 Lakh ITR (Self-Employed)
Min CIBIL: 730+
“The ₹1.2 Lakh annual waiver makes BOB Premier practically free for any working professional. You get genuine domestic airport lounge access and 5X dining rewards without predatory fine print.”
Novio Secured RuPay Credit Card
Issued by Scheduled Commercial Bank Engine (Credilio Co-Branded) • Optimized for Credit beginners, students, housewives, and individuals rebuilding damaged CIBIL scores.
Joining Fee
₹0 (Zero Joining Fee)
Annual Renewal Fee
₹0 (Lifetime Free)
Fee Waiver Condition
No spend criteria (Always Free)
Airport Lounge Access
No complimentary lounge visits
Key Advantages & Standout Features
- 100% Guaranteed approval: Zero salary slips, zero ITR documents, and zero prior credit score needed.
- Deposit earns high fixed deposit interest (up to 7.5% p.a.) compounding safely in an RBI-regulated bank.
- Credit limit equals up to 90%–100% of your fixed deposit (start with as low as ₹2,000 to ₹10,000).
- Reports monthly credit performance to all 4 credit bureaus (CIBIL, Experian, Equifax, CRIF) to build a 750+ score.
- RuPay card platform enables instant linking to UPI applications for everyday QR code merchant spending.
Limitations & Exclusions to Note
- Requires upfront fixed deposit commitment; your money remains locked as collateral during card usage.
- Premature liquidation of the fixed deposit automatically triggers credit card account cancellation.
- Does not provide airport lounge access or high-tier travel insurance coverage.
- Cash advance from ATMs against your own FD incurs interest charges and should be avoided.
Age: 18+ Years
Income: None (Zero Income Proof Required)
Min CIBIL: None Required (Score 0, -1, or low CIBIL accepted)
“After a default on a personal loan ruined my CIBIL to 610, every bank rejected me. I opened a ₹10,000 FD with Novio, kept my utilization at 25%, and reached a 765 CIBIL score in just 7 months.”
RBI Master Directions on Credit Cards (2027 Regulatory Rules)
Understanding cardholder rights, billing cycle modification rules, and interest calculation mandates enforceable under Reserve Bank of India regulations.
The regulatory architecture governing credit cards in India is governed by the Reserve Bank of India (Credit Card and Debit Card – Issuance and Conduct) Directions, 2022, read alongside amendments enforced through 2026 and 2027. Every cardholder is protected by statutory provisions that prohibit predatory banking behavior:
1. One-Time Billing Cycle Choice
Under RBI directions, cardholders must be given the option to modify their credit card billing cycle start date at least once, allowing you to align statement due dates with your salary credit date.
2. Key Fact Statement (KFS)
Banks are legally prohibited from hiding fees. Every card issuer must provide a standardized Key Fact Statement displaying the exact Annual Percentage Rate (APR), late fees, and forex markups prior to onboarding.
3. Mandatory Consent for Limit Hike
Banks cannot unilaterally increase your credit limit or activate paid insurance add-ons without explicit OTP-authenticated written or digital consent from the primary cardholder.
RBI Warning on "Minimum Amount Due" (MAD) Trap:
Paying only the Minimum Amount Due (typically 5% of your statement balance) does NOT stop interest charges. The moment you fail to pay the Total Amount Due in full, you lose your 50-day interest-free grace period completely. All subsequent transactions begin accruing compounding finance charges at 36% to 42% per annum from the exact transaction date, subject to 18% GST on interest charges!
Step-by-Step SOP: Online Application & Approval Without Rejection
Follow this standard operating procedure to maximize instant digital approval and prevent unnecessary hard inquiries on your CIBIL record.
Check Your Free CIBIL Score Before Submitting Applications
Ensure your credit score is 750 or higher. Verify there are zero overdue payments, incorrect loan listings, or settled accounts on your credit report.
Apply Through Official Direct Affiliate & Bank Links
Click the direct online application button for your chosen card. Complete the primary form using the exact legal name and mobile number linked to your Aadhaar and bank accounts.
Complete Instant Aadhaar OTP & Video KYC (V-KYC)
Keep your original physical PAN card handy. Join the 2-minute video call with the bank officer in a well-lit quiet room. Successful V-KYC eliminates physical home/office verification visits.
Activate Virtual Card & Enable Domestic Online/UPI Spends
Once approved, download the bank's official mobile application. Activate your virtual card details, set a safe daily transaction limit, and link your RuPay cards to your preferred UPI app.
Recommended Video Reviews & Practical Tutorials
Watch these verified, high-authority video comparisons by prominent Indian personal finance practitioners covering real-world card usage.
Frequently Asked Questions (Credit Cards India 2027)
Answers to high-frequency applicant questions regarding card issuance, fees, CIBIL scores, and lounge regulations.
Which credit card is best for someone applying for their very first card in India?
If you have no prior credit score or income proofs, the Novio Secured RuPay Credit Card is the #1 choice because it guarantees 100% approval against a minimal fixed deposit while reporting to CIBIL. If you have an active salary account with ₹25,000+ monthly income, the IDFC FIRST Classic Card is ideal due to its zero joining fee, zero annual fee (Lifetime Free), and transparent dynamic APR.
What is the difference between direct cashback cards and reward point cards?
Direct cashback cards (like SBI Cashback and Airtel Axis) credit real money directly onto your credit card statement, immediately reducing your billing liability without any conversion fees or expiration dates. Reward point cards (like Tata Neu or BOB Premier) accumulate points or coins that must be redeemed inside specific partner catalogs, airline tickets, or hotel vouchers.
Can I get my annual credit card fee waived automatically?
Yes. Every credit card with an annual renewal fee specifies an annual spend threshold (typically between ₹1,20,000 and ₹3,00,000 per calendar year). If your cumulative transactions cross this benchmark, the annual fee is 100% reversed on your anniversary statement. Cards like Federal Scapia, IDFC FIRST Classic, Kiwi, and Novio are 100% Lifetime Free without any annual spend requirements.
Does checking credit card eligibility or applying online damage my CIBIL score?
Checking pre-approved offers on official bank portals triggers a 'Soft Inquiry', which has zero negative impact on your credit score. However, submitting multiple official credit card applications to 4 or 5 different banks simultaneously causes multiple 'Hard Inquiries' on your CIBIL profile, which can temporarily reduce your score by 15–30 points. Apply to one card at a time with a 60-day gap.
What should I do if a bank levies an unexpected annual fee or charges high interest?
Under the RBI Master Direction on Credit Card Issuance, banks must transparently communicate all charges in the Key Fact Statement (KFS). If an unexpected fee is levied contrary to terms, lodge a written grievance with the bank's nodal officer. If unresolved within 30 days, file an online grievance with the RBI Banking Ombudsman on cms.rbi.org.in.
Verified Cardholder Feedback (X, LinkedIn & Facebook Groups)
Real-world experiences, reward optimization strategies, and warnings gathered from active Indian financial practitioners and community threads.
Anupam Agrawal, Chartered Accountant
Financial Markets & Credit Risk Advisory
“The fatal mistake Indian cardholders make is collecting 10 different cards with ₹1,000 annual fees and failing to meet the fee waiver thresholds. If your annual spend is under ₹4 Lakh, hold strictly 2 cards: one 5% online cashback card (SBI Cashback) and one 0% forex or lifetime-free RuPay UPI card (Scapia or Kiwi).”
Shreya Ghoshal-Bose, Fintech Columnist
CardExpert & Personal Finance Lead
“Banks have quietly tightened domestic airport lounge rules across India for 2026-2027. Almost all major issuers now demand ₹10,000 to ₹50,000 in quarterly transaction volume to generate a valid lounge QR code. Federal Scapia remains the rare exception with a realistic ₹5,000 monthly spend threshold.”
Venkatesh Iyer, Software Architect
Bangalore Tech Enthusiasts Community
“Using the Tata Neu Infinity RuPay card for regular UPI QR payments at local vegetable markets, pharmacies, and bakeries generated over ₹14,000 in NeuCoins for my family this year. We paid for our entire Diwali airfare on Air India completely free using those coins.”
Deepak Shenoy, Capital Markets Analyst
Macro & Consumer Debt Researcher
“Never revolving your balance is the cardinal rule of credit cards. Paying only the 'Minimum Amount Due' triggers 42% APR plus 18% GST on interest charges from Day 1. Treat a credit card as a 50-day interest-free debit card, automate full statement auto-debit, and your CIBIL score will cross 780 naturally.”